The HDB Silver Housing Bonus: up to $40,000 for right-sizing
A Singapore citizen household with an owner aged 55 or above that sells its home and buys a 3-room or smaller HDB flat can receive up to $30,000 in cash by committing up to $60,000 to CPF Retirement Accounts, and another $10,000 if the new flat is a 2-room or smaller flat or a Community Care Apartment. The commitment can come from the CPF housing refund, so no cash top-up may be needed.
Who qualifies
| Condition | Requirement |
|---|---|
| Citizenship | At least one owner is a Singapore citizen |
| Age | That citizen is 55 or above |
| Gross monthly household income | $16,000 or less |
| Home you sell | An HDB flat past its minimum occupation period, or private residential property with an annual value of up to $31,000 |
| Home you buy | A 3-room flat (not a 3-room terrace), or a 2-room or smaller flat including a Community Care Apartment |
| Proceeds | Positive net sale proceeds |
| Timing | Book or apply for the new flat before the sale, or within 12 months of completing it; apply for the bonus within a year of the second completion |
How much you get
| Home you sell | Bonus for the $60,000 commitment | Extra for 2-room or smaller | Maximum |
|---|---|---|---|
| HDB flat, or private with annual value $21,000 or less | Up to $30,000 ($1 for every $2 committed) | $10,000 | $40,000 |
| Private with annual value between $21,000 and $31,000 | Up to $10,000 ($1 for every $6 committed) | $10,000 | $20,000 |
The commitment is capped at $60,000 per household and by the prevailing Full Retirement Sum. The extra $10,000 for a 2-room or smaller flat is not pro-rated.
HDB's own example
A senior couple sell a 5-room flat in Yishun for $705,000, with $100,000 of loan left, buy a new 3-room flat in Woodlands for $275,000, and pay a $45,000 resale levy. Net proceeds are $285,000. Their CPF housing refunds of $40,000 and $20,000 are committed to their Retirement Accounts, so no cash top-up is needed, and they receive $30,000.
What it means for your retirement income
The committed sum joins CPF LIFE and raises the monthly payout for life. The cash from the sale, less the new flat, is on top. Freedom Age shows both on your numbers: the age at which the right-sizing move pays the income you want, compared with keeping the home and renting out a room or the whole flat.
A worked example: a couple of 62 and 60 in a fully paid 5-room flat
The worked example follows a couple of 62 and 60 in a fully paid 5-room flat in District 18 worth S$750,000, with S$180,000 of CPF used on it. They earn S$4,000 and S$2,000 a month and want S$3,500 a month in retirement.
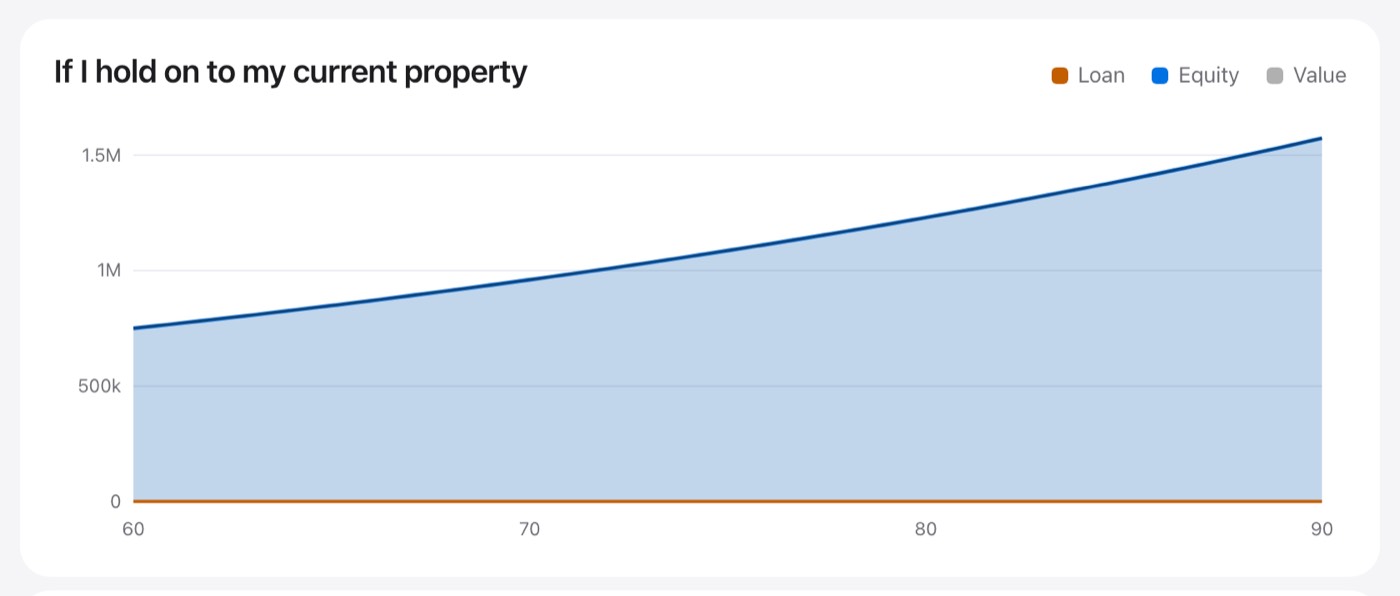
Keeping the flat, Freedom Age shows it worth about S$848,556 at 65, with nothing owed. That is wealth, but not income: it pays nothing a month until something is done with it. Their chosen move is to sell and buy a smaller home with cash in hand.
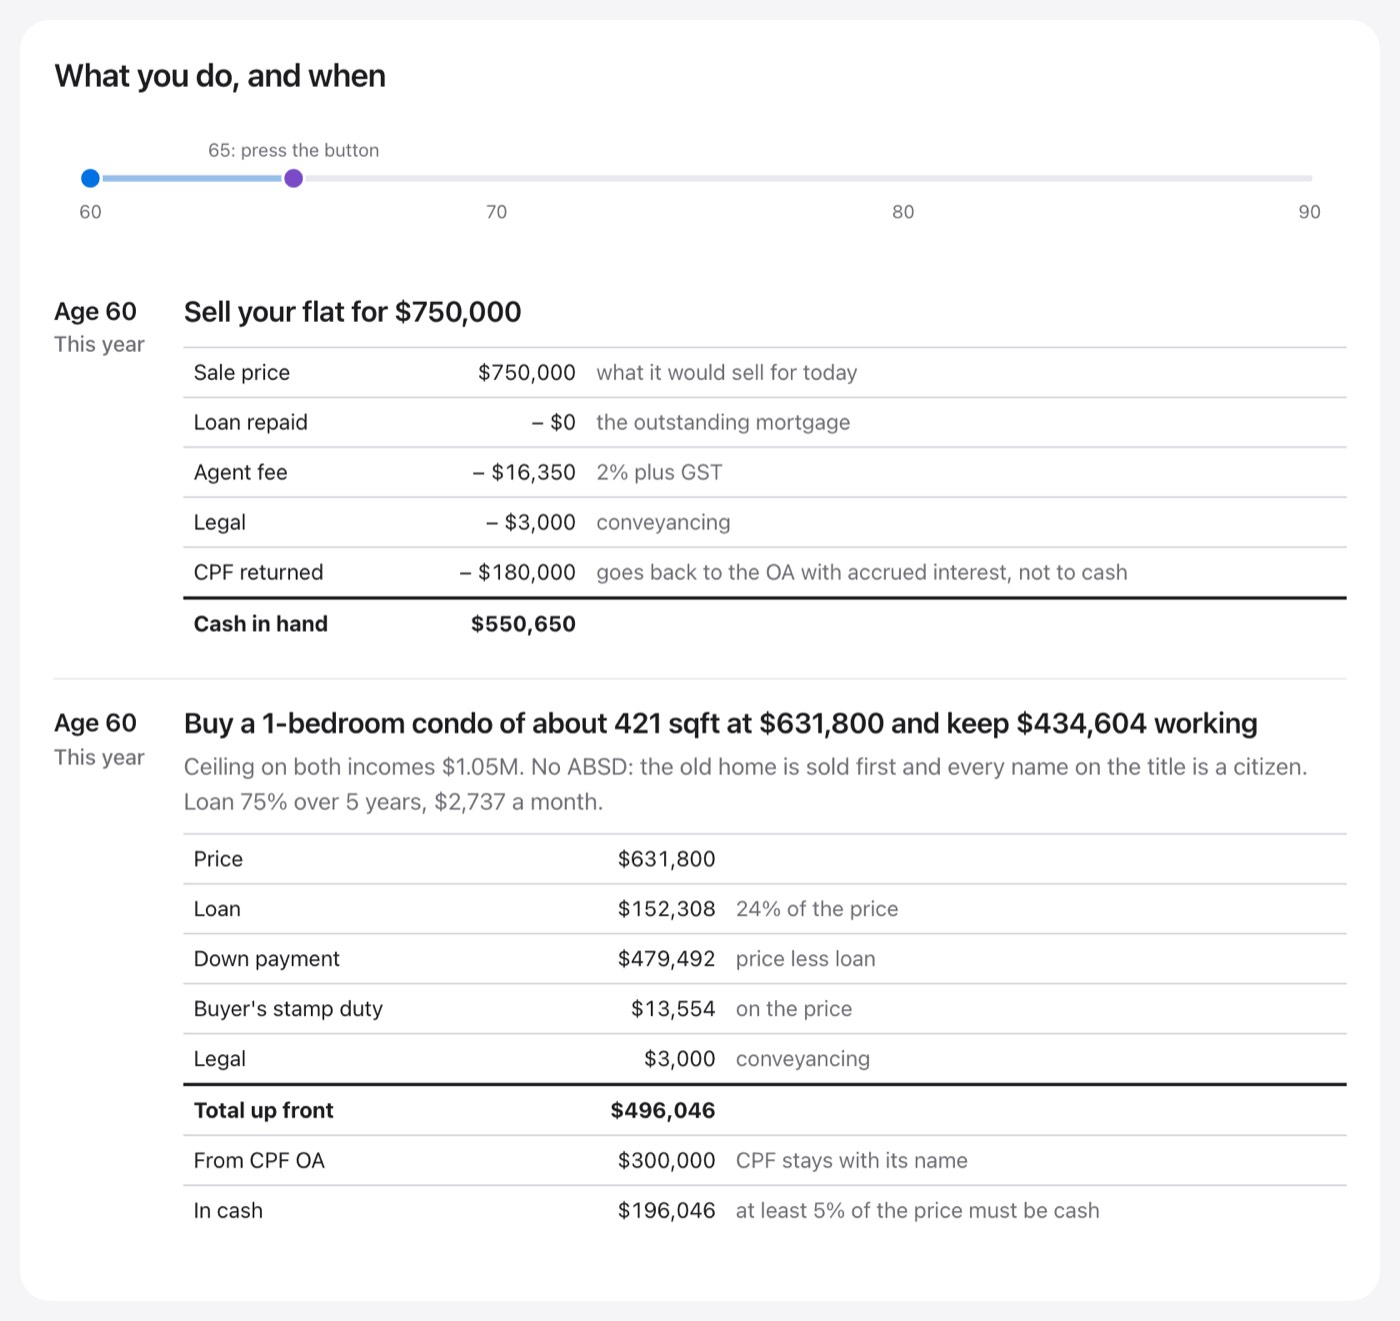
| The sale | |
|---|---|
| Sale price | S$750,000 |
| Agent fee (2% plus GST) | − S$16,350 |
| Legal | − S$3,000 |
| CPF returned to the Ordinary Accounts | − S$180,000 |
| Cash in hand | S$550,650 |
The tool sizes the next home to what the bank would lend and what keeps money working: a 1-bedroom condominium of about 405 square feet at S$608,400, a short loan of S$111,773 over three years at S$3,250 a month, and S$418,171 kept working. CPF pays S$1,380 of each instalment and S$1,870 comes from salary. The move turns a home that pays nothing into a smaller home plus a pot that pays, at the cost of three years of instalments that run to 65.
Silver Housing Bonus, step by step
- Check the household: a Singapore citizen owner aged 55 or above, gross household income of S$16,000 a month or less.
- Check the home you sell: an HDB flat past its MOP, or private property with an annual value up to S$31,000 (the bonus is smaller above S$21,000).
- Pick the next home: a 3-room (not a 3-room terrace) or smaller flat, including a Community Care Apartment.
- Time it: book or apply for the new flat before selling, or within 12 months of completing the sale.
- Commit up to S$60,000 to your Retirement Accounts from the CPF housing refund, then apply within a year of the second completion.
Where the bonus sits in a retirement plan
The bonus is cash on top of a move that already releases money. In HDB's own example a couple selling a 5-room flat for S$705,000 and buying a 3-room flat receives S$30,000; the larger gain is the net proceeds of S$285,000 and the higher CPF LIFE payout from the committed sum. Freedom Age's example above shows the same logic for a 5-room household: the move matters more than the bonus, and the bonus rewards making it.
Common mistakes
- Buying a 4-room. It does not qualify; the next flat must be 3-room or smaller.
- Missing the 12 months. The new flat must be booked or applied for within 12 months of the sale.
- Topping up in cash unnecessarily. Since December 2025 the commitment can come from the CPF housing refund.
The bottom line
The Silver Housing Bonus rewards right-sizing to a 3-room or smaller flat with up to $40,000, but the larger gain is usually the move itself: the net proceeds and a higher CPF LIFE payout.
find the age your own home could start paying you: five questions, free.
Find my Freedom Age
The check is free and needs no account. Two optional paid plans: the Freedom Plan, S$199 one-time, and the Freedom Plan with a 45-minute consultation, S$449 one-time. Nothing renews. Prices and terms.
Questions people ask
- Do I have to top up $60,000 in cash to get the Silver Housing Bonus?
- No. Since 1 December 2025 the commitment can come from your CPF housing refund. If you commit less than $60,000, the bonus is pro-rated.
- Can condo owners get the Silver Housing Bonus?
- Yes, if the private property has an annual value of up to $31,000 and the household meets the other conditions. Above an annual value of $21,000 the bonus is smaller: up to $10,000, plus $10,000 for a 2-room or smaller flat.
- Does a 4-room flat qualify?
- No. The flat you buy must be a 3-room (not a 3-room terrace) or smaller, including a Community Care Apartment.
- What is the maximum Silver Housing Bonus?
- $40,000 per household: $30,000 for the full $60,000 commitment and $10,000 more for right-sizing to a 2-room or smaller flat.
- Can I get the Silver Housing Bonus and still buy a resale flat?
- Yes, if it is a 3-room or smaller flat and the other conditions are met; the bonus covers new and resale flats of those types.
- Does a private property owner get the full Silver Housing Bonus?
- Only if the property's annual value is S$21,000 or less; between S$21,000 and S$31,000 the bonus is up to S$10,000, plus S$10,000 for a 2-room or smaller flat (HDB).