Selling a condo to buy an HDB flat: the rules, the order and the money
You can buy a non-subsidised HDB resale flat first and sell the condo within six months, with no wait-out, provided you do not take an HDB loan. The move frees the condo's net proceeds, less what the flat takes from your cash and CPF. Part of the proceeds goes back to your CPF as a housing refund; the rest is cash you can turn into a monthly income.
The rules that decide the order
- No wait-out for a non-subsidised resale flat bought with a bank loan or cash (since 28 July 2026).
- Six months to complete the sale of the private property after the flat purchase completes.
- 30 months of waiting if you want an HDB loan, a CPF housing grant, a new flat from HDB or a new EC.
- Five-year minimum occupation period on the flat you buy (ten years for Plus and Prime flats) before you can sell it, rent out the whole flat, or buy private property again.
Where the money goes when the condo sells
From the sale price come the outstanding loan, the agent's fee and legal costs. Then the CPF you used for the condo, with the accrued interest, goes back to your CPF accounts as a housing refund. What is left is cash. The flat is paid for with a bank loan if you take one, your CPF and cash (with a bank loan, at least 5% of the price must be cash), and the cash that remains, with any savings you already hold, is the sum that can pay you. The worked example below shows each step.
If you are 55 or older, you may be able to add a Silver Housing Bonus of up to $30,000 per household by right-sizing to a 3-room or smaller flat and committing up to $60,000 to your CPF Retirement Account; the private property must have an annual value of up to $31,000 (the bonus is smaller above $21,000). See the Silver Housing Bonus guide.
When not to do it
If the condo is under three years old in your hands, seller's stamp duty applies. If you need an HDB loan, the 30-month wait returns, and with it a long spell of renting. And if your goal is income rather than space, keeping the condo and renting it out can beat selling; the answer turns on the rent, the loan left and your age.
A worked example: a condominium couple of 58 and 56 right-sizing
Freedom Age's worked example follows a couple of 58 and 56 in a District 15 condominium worth S$1.6 million, with S$200,000 of loan left and S$420,000 of CPF used on the purchase. They earn S$9,000 and S$6,000 a month and name S$5,000 a month as the retirement income they want. Their chosen move: sell, buy an HDB resale flat, invest the rest.
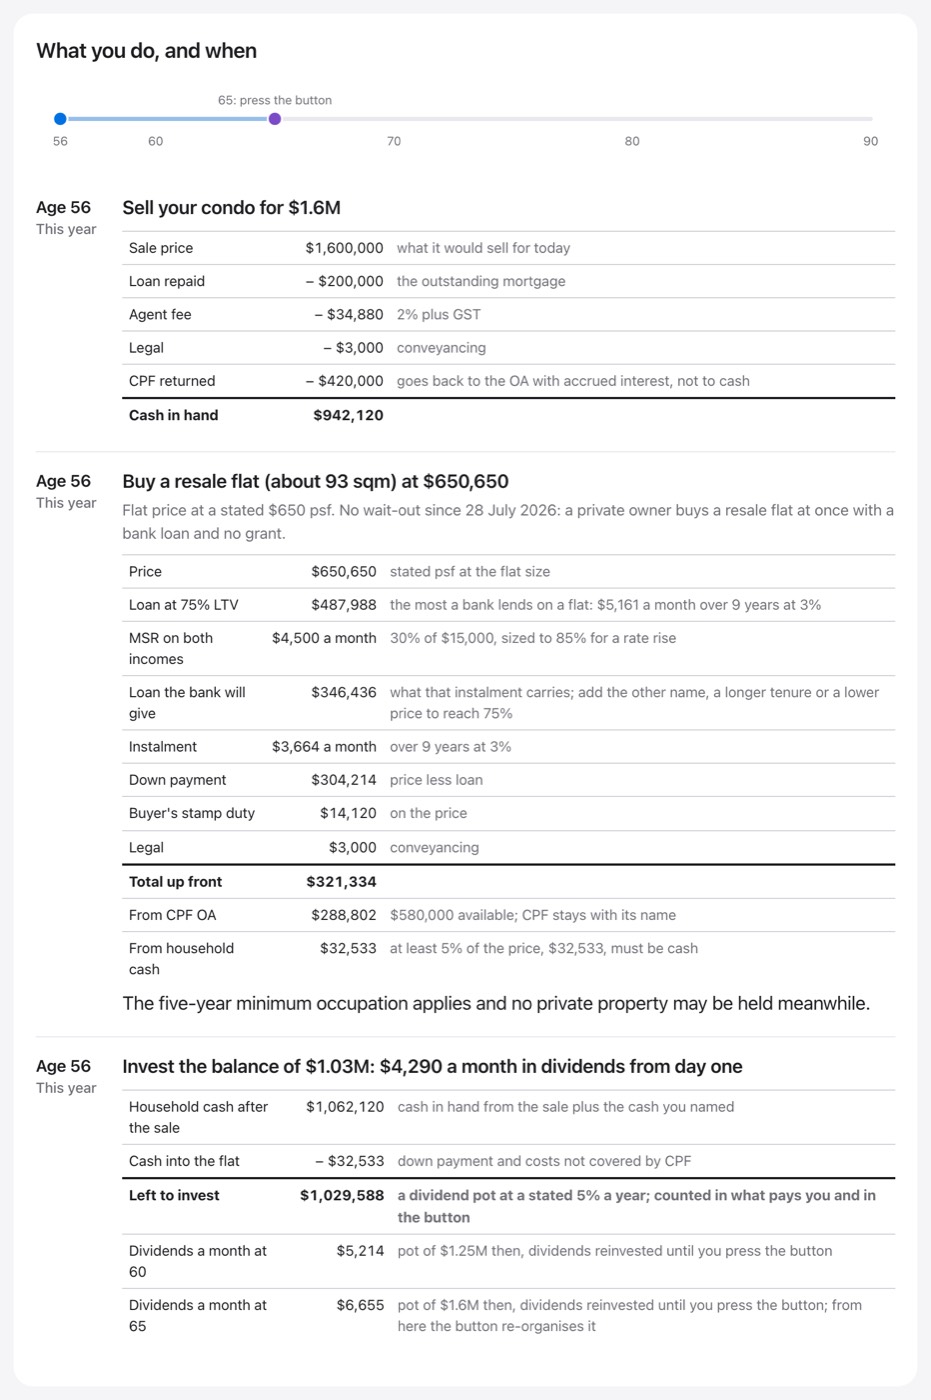
| The sale | |
|---|---|
| Sale price | S$1,600,000 |
| Loan repaid | − S$200,000 |
| Agent fee (2% plus GST) | − S$34,880 |
| Legal | − S$3,000 |
| CPF returned to the Ordinary Accounts | − S$420,000 |
| Cash in hand | S$942,120 |
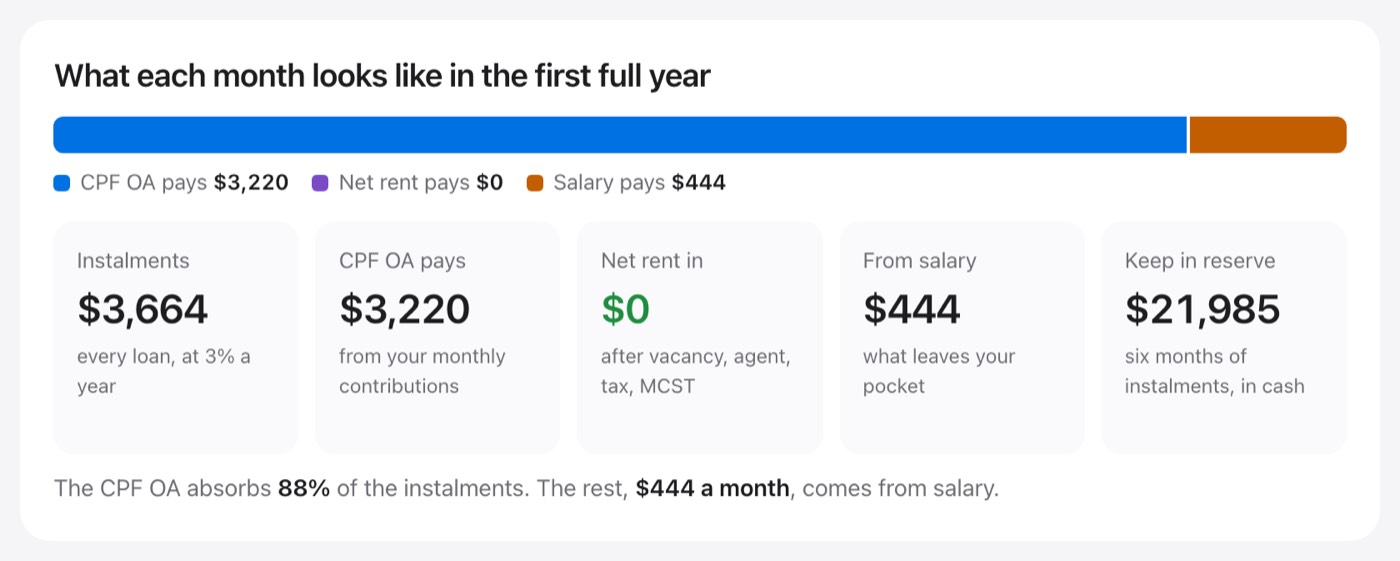
The flat, about 93 square metres, is priced at S$650,650 on a stated S$650 per square foot. Because they buy without an HDB loan there is no wait-out. The bank would lend up to 75%, but two limits bite: banks lend to about 65, so at 58 and 56 the loan runs only seven years, and the mortgage servicing ratio on their two incomes caps the instalment. What the loan does not cover, with the stamp duty and legal fees, comes from S$306,022 of CPF and S$32,532.50 of cash, the 5% of the price that must be paid in cash. The instalment is S$4,350 a month: CPF pays S$3,220 of it and S$1,130 comes from salary.
So they have more to invest than the sale's cash in hand: the flat takes only S$32,532.50 of their cash, and they already held S$120,000 of savings.
| What is left to invest | |
|---|---|
| Cash in hand from the sale | S$942,120 |
| Savings they already held | + S$120,000 |
| Cash into the flat (5% of the price) | − S$32,532.50 |
| Left to invest | S$1,029,588 |
At the tool's stated 5% a year, S$1,029,588 could pay about S$4,290 a month in dividends from the day they move.
How the money moves, step by step
- Sale price, less the outstanding loan.
- Less the agent fee (typically 2% plus GST) and legal fees.
- Less the CPF used for the property, with accrued interest, which returns to your CPF accounts.
- What remains is cash. The flat is paid for with a bank loan if you take one, your CPF and cash; with a bank loan, at least 5% of the price must be cash.
- The cash left after the flat, with any savings you already hold, is the sum that can pay you: invested, kept as a reserve, or both.
What the move changes each month
In the example, the flat's instalment is S$4,350 a month over seven years, of which CPF pays S$3,220 and salary S$1,130. The invested balance could pay about S$4,290 a month in dividends at the tool's stated 5%. The household swaps a condominium that paid nothing into a flat plus an income: the core of right-sizing.
Common mistakes
- Forgetting the MSR. An HDB flat bought with a bank loan is still capped at a 30% mortgage servicing ratio; the example's loan is capped by it, not by the 75% loan-to-value.
- Buying the same size again. The income comes from the gap between the two homes; a flat as large as the condo leaves little to invest.
- Leaving no reserve. Hold six months of instalments in cash; in the example that is S$26,100.
The bottom line
Selling a condo to buy an HDB flat can free a large sum for retirement, but only the cash left after the loan, the fees and the CPF refund is yours to invest. Size the flat to leave that sum working.
find the age your own home could start paying you: five questions, free.
Find my Freedom Age
The check is free and needs no account. Two optional paid plans: the Freedom Plan, S$199 one-time, and the Freedom Plan with a 45-minute consultation, S$449 one-time. Nothing renews. Prices and terms.
Questions people ask
- Do I need to sell my condo before buying an HDB flat?
- No. Without an HDB loan you can buy the resale flat first and must complete the condo sale within six months of the flat purchase.
- Can I use my CPF to buy the HDB flat after selling my condo?
- Yes. The CPF refunded from the condo sale returns to your Ordinary Account and can be used for the flat, subject to CPF's usage limits.
- Do I pay ABSD if I buy the HDB flat before selling my condo?
- Not if any buyer is a Singapore citizen: IRAS fully remits ABSD on the acquisition of an HDB flat when the buyer or any joint buyer is a citizen, granted automatically on HDB's approval. A household of permanent residents pays ABSD at 5% on the flat.
- Is there a minimum occupation period on the resale flat?
- Yes. Five years for a Standard or older unclassified flat, ten years for Plus and Prime flats, before you can sell it or buy private property again.
- What is the mortgage servicing ratio for an HDB flat?
- Banks cap the instalment on an HDB flat at 30% of gross monthly income, on top of the 55% total debt servicing ratio.
- How much could a right-sizing move pay each month?
- It depends on the gap between the two homes. In Freedom Age's example, about S$1.03 million invested at a stated 5% could pay about S$4,290 a month.