Four ways your home can pay you in retirement
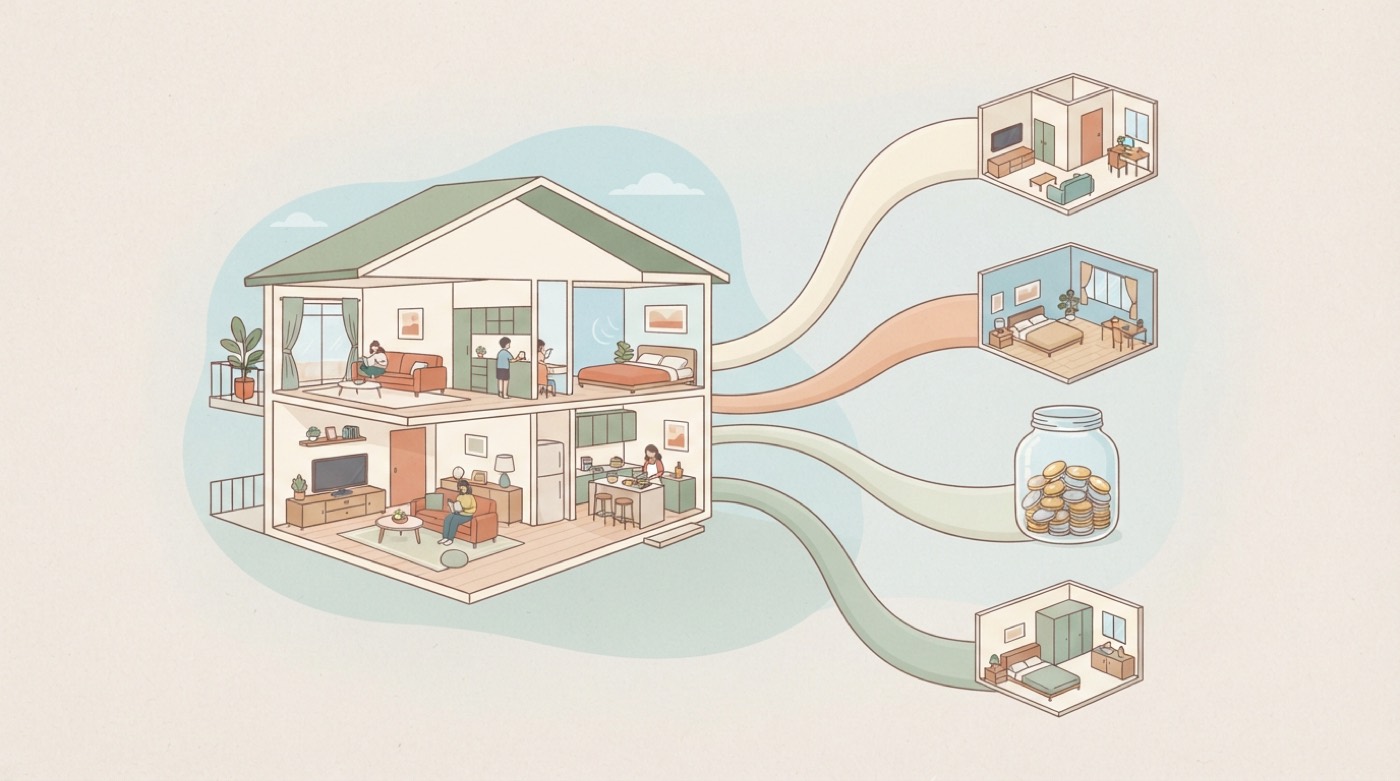
A Singapore home turns into a monthly income in one of four ways: sell and right-size, freeing cash and CPF for CPF LIFE and investments; rent out a room or the whole home; sell the tail end of an HDB lease back to HDB under the Lease Buyback Scheme; or buy a second property earlier in life and let its rent and growth carry you. Which one works, and at what age, depends on what you own, what you owe and what you earn.
1. Sell and right-size
The largest release of cash. Private owners can now buy a non-subsidised resale flat without the 15-month wait if they skip the HDB loan (how it works). Seniors buying a 3-room or smaller flat can add the Silver Housing Bonus of up to $40,000.
2. Rent out a room or the whole home
Keeps the asset and its growth. HDB owners of a 3-room or larger flat can rent out spare bedrooms with approval; the whole flat only after the MOP, and never for Plus and Prime flats. A condominium can be let whole at any time.
3. The Lease Buyback Scheme
For HDB owners aged 65 and above who want to stay put: sell part of the lease, top up the Retirement Account, receive a bonus of up to $30,000 and a CPF LIFE payout, and keep up to $100,000 in cash (the full rules).
4. Keep and add, earlier
The route that needs time: after the MOP, buy a second property while incomes are high, so that by your fifties one of the two can be sold to clear the other or both can be let. It carries ABSD and a second loan, and it is the one where the timing matters most (what the MOP allows).
How Freedom Age decides between them
Freedom Age asks five questions: who is planning and their ages, what you earn, what you own and owe, the monthly income you want in retirement, and where you want to go next. It prices every route that fits your household on the loan rules (TDSR 55%, a 4% stress test, 75% loan-to-value on a first housing loan), stamp duties and CPF, and returns one number: the age at which your property could start paying you that income.
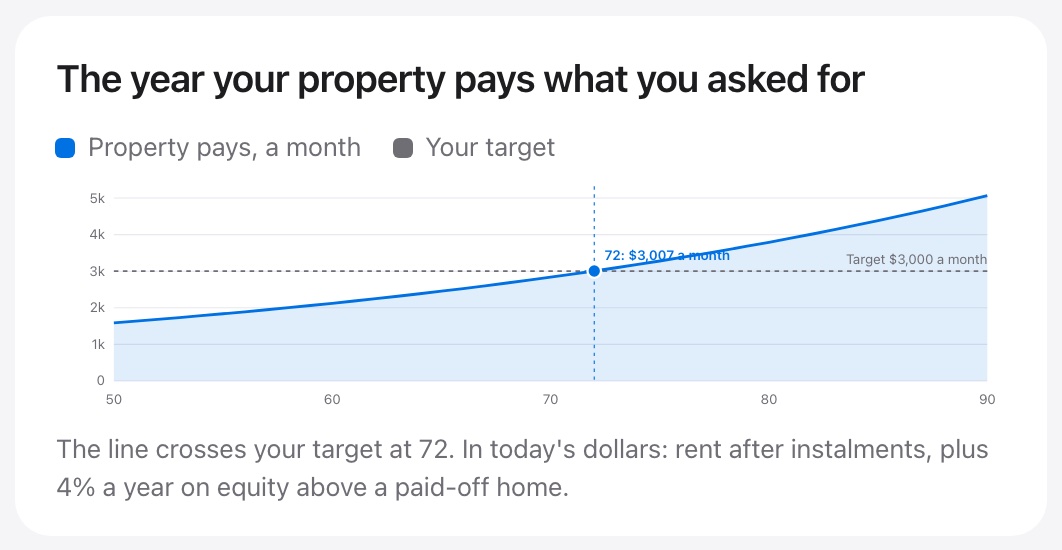
Then it shows the moves that bring the age forward and the year to press the button.
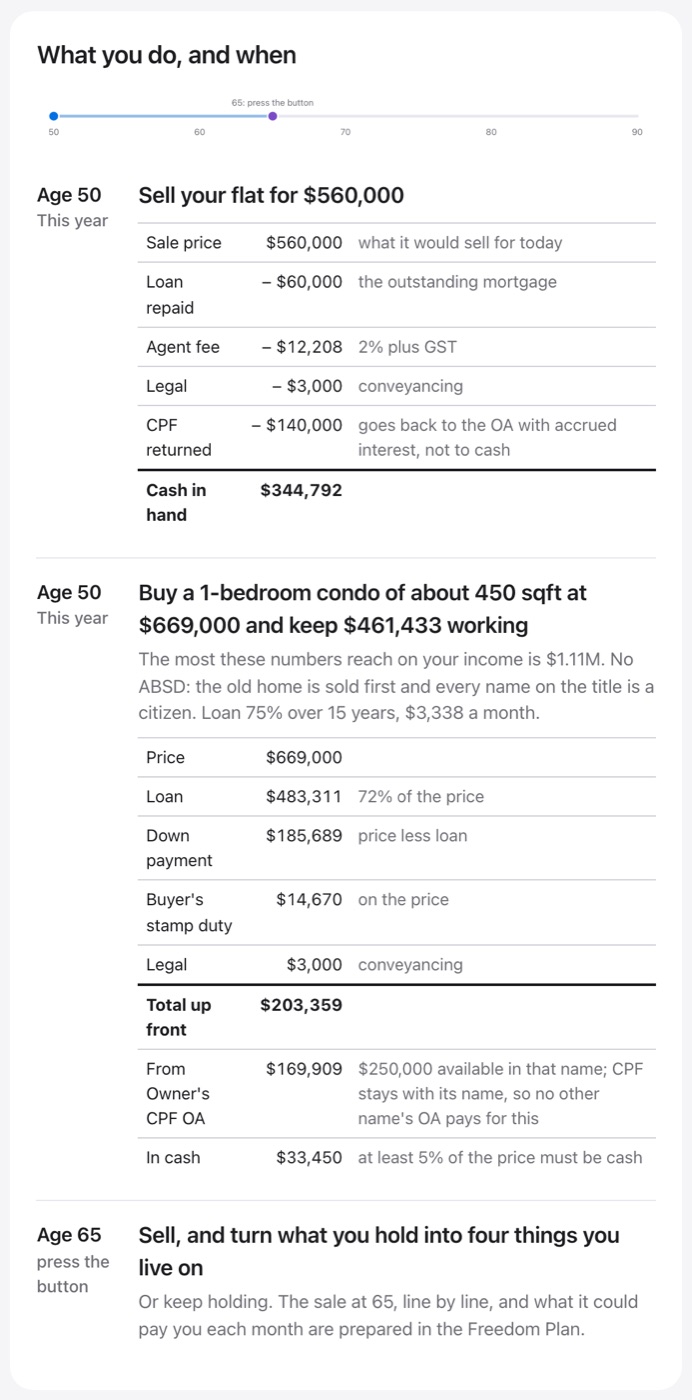
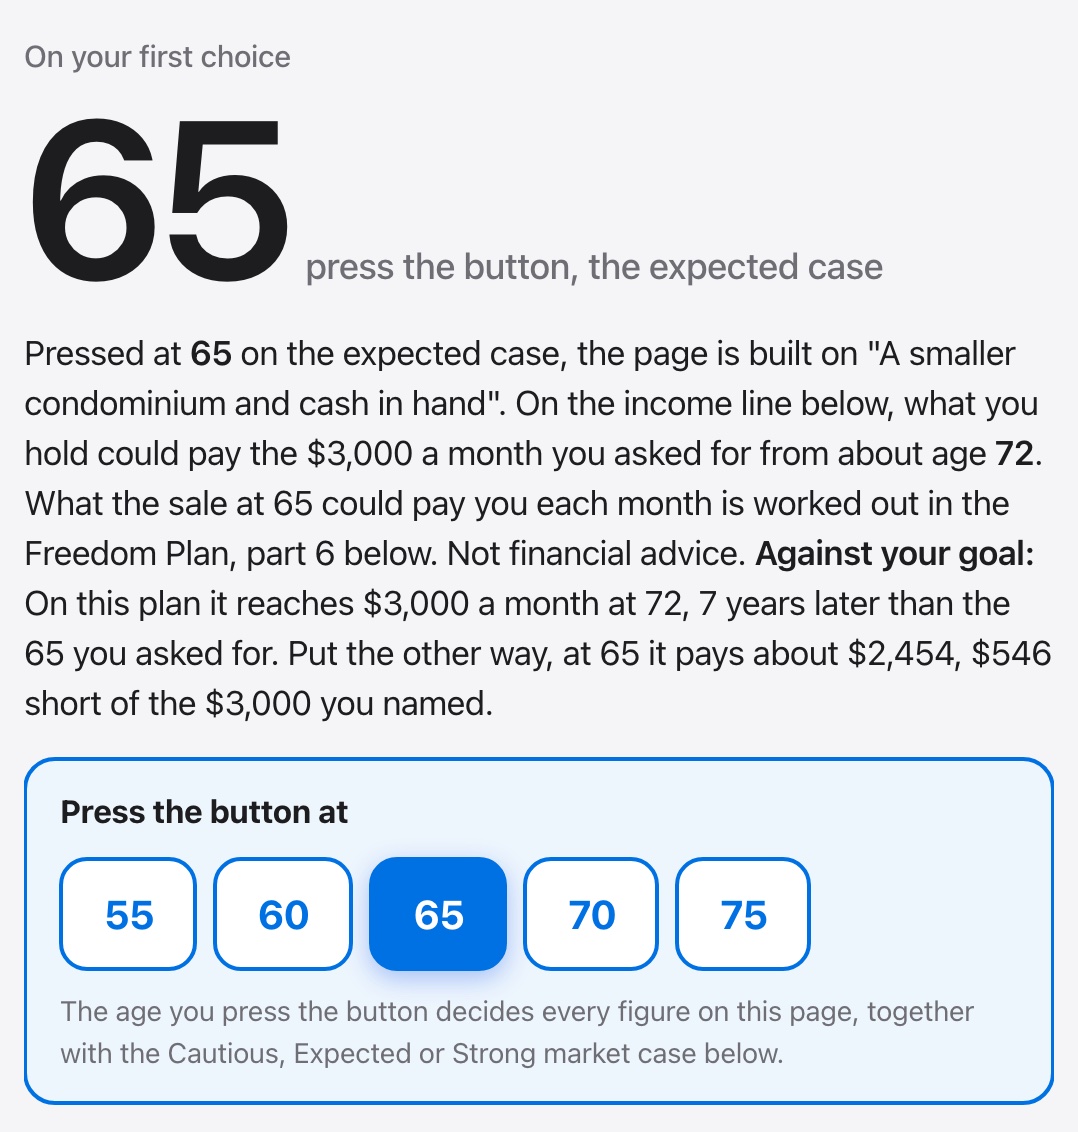
A worked example: a couple of 62 and 60 in a fully paid 5-room flat
The worked example follows a couple of 62 and 60 in a fully paid 5-room flat in District 18 worth S$750,000, with S$180,000 of CPF used on it. They earn S$4,000 and S$2,000 a month and want S$3,500 a month in retirement.
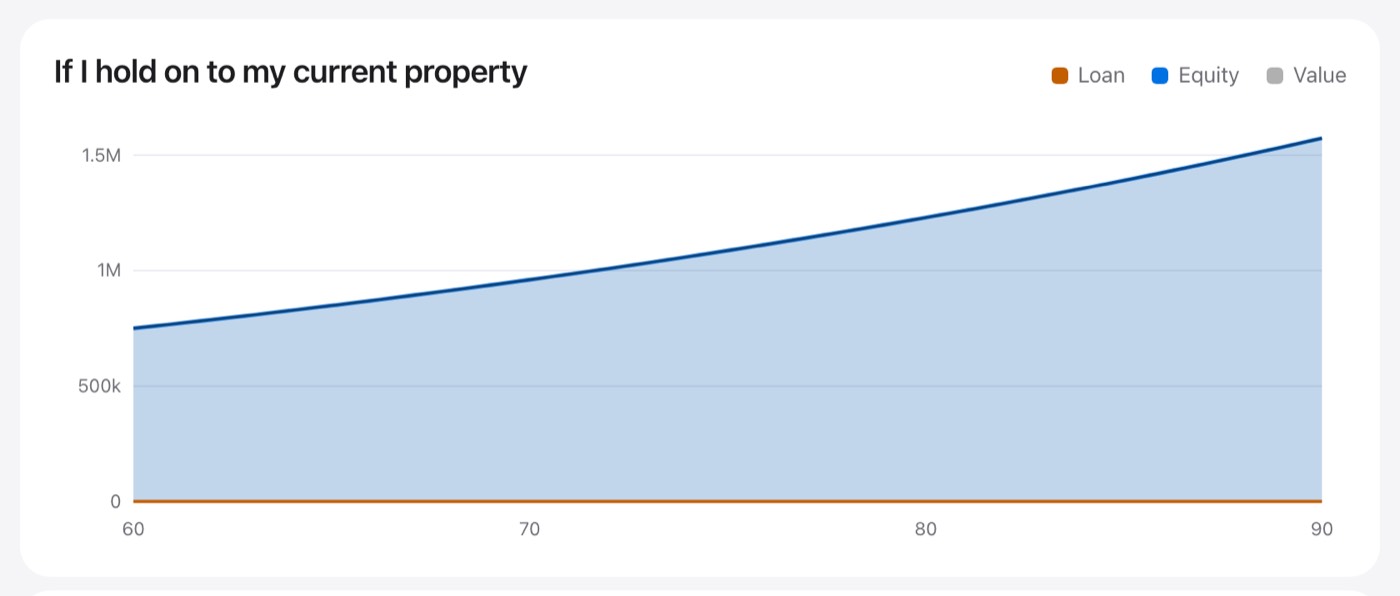
Keeping the flat, Freedom Age shows it worth about S$848,556 at 65, with nothing owed. That is wealth, but not income: it pays nothing a month until something is done with it. Their chosen move is to sell and buy a smaller home with cash in hand.
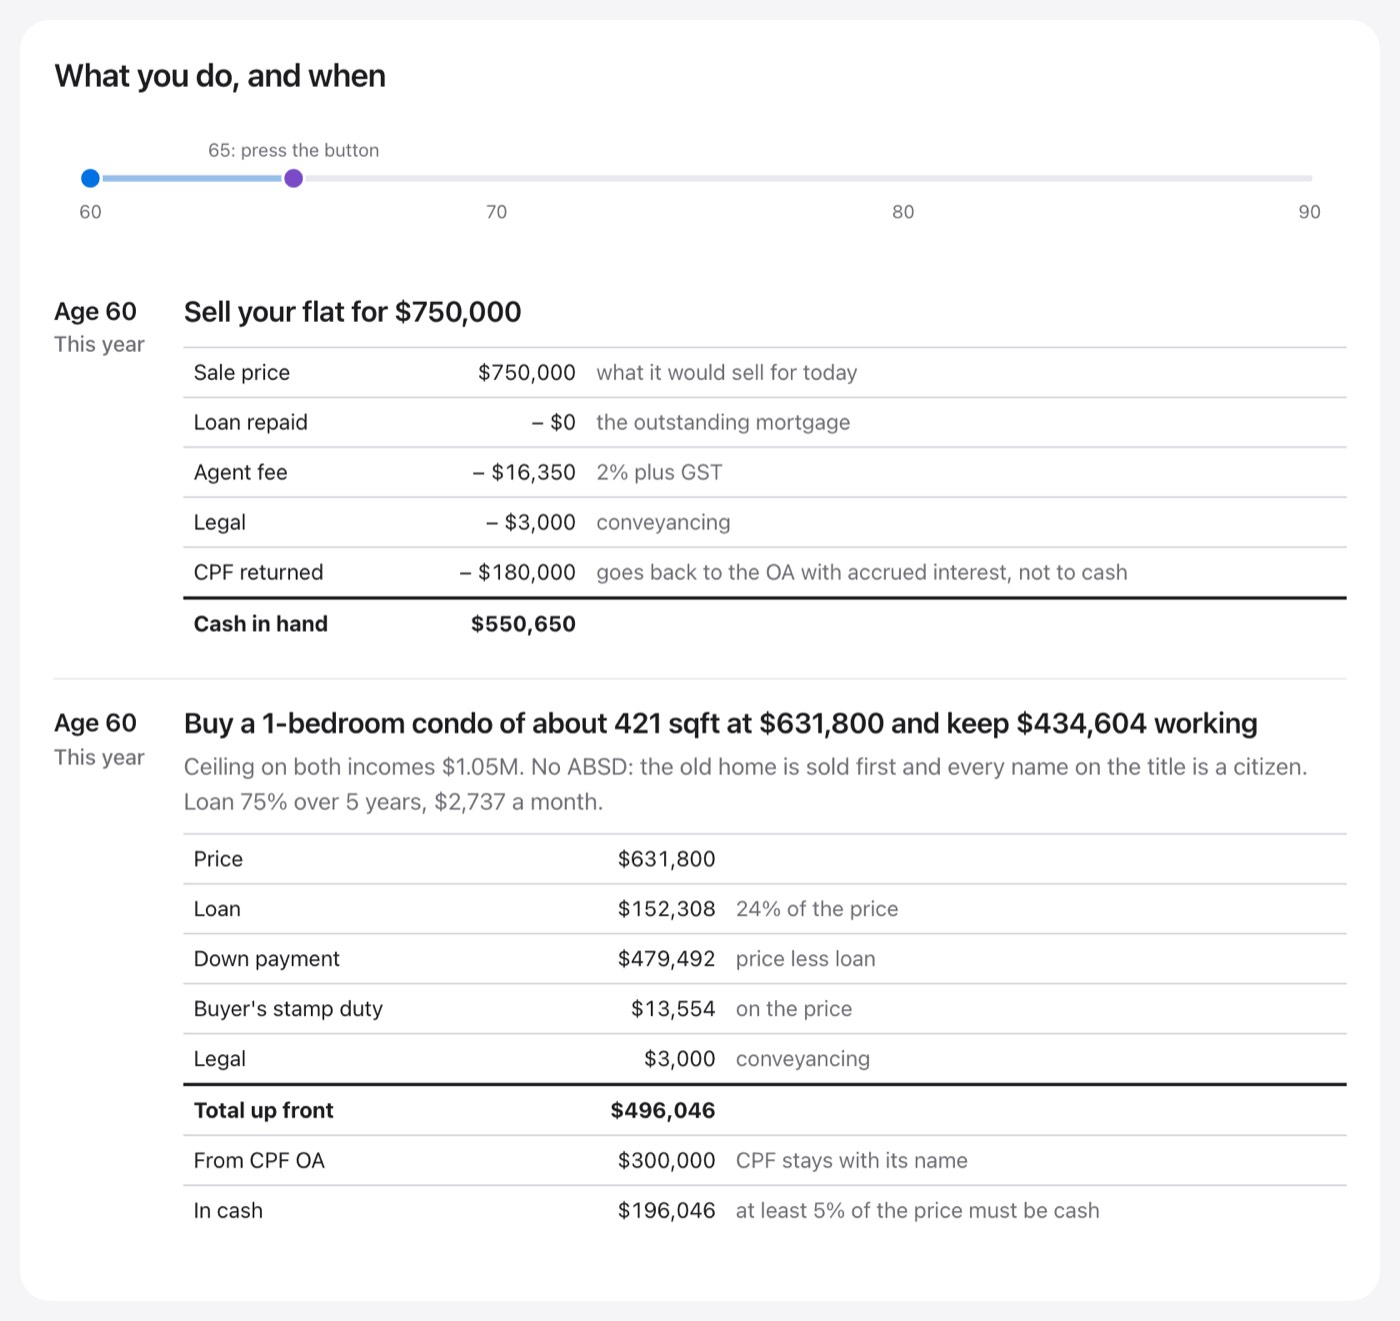
| The sale | |
|---|---|
| Sale price | S$750,000 |
| Agent fee (2% plus GST) | − S$16,350 |
| Legal | − S$3,000 |
| CPF returned to the Ordinary Accounts | − S$180,000 |
| Cash in hand | S$550,650 |
The tool sizes the next home to what the bank would lend and what keeps money working: a 1-bedroom condominium of about 405 square feet at S$608,400, a short loan of S$111,773 over three years at S$3,250 a month, and S$418,171 kept working. CPF pays S$1,380 of each instalment and S$1,870 comes from salary. The move turns a home that pays nothing into a smaller home plus a pot that pays, at the cost of three years of instalments that run to 65.
Which route suits which household
| Household | Often suits |
|---|---|
| Home fully paid, 65 or older, wants to stay | Lease Buyback, or renting a room |
| Home larger than needed, 55 or older | Sell and right-size, with the Silver Housing Bonus if eligible |
| Condominium owners wanting cash | Sell and buy an HDB resale flat (no wait-out without an HDB loan) |
| Forties, flat past MOP, strong incomes | Upgrade, or keep and add, while the bank still lends long |
Five questions to answer first
- What monthly income do you want, in today's dollars?
- At what age do you want it to start?
- How much of the home is yours today, after the loan and the CPF refund?
- Are you willing to move?
- What do you want to leave, and to whom?
The bottom line
Your home is likely your largest retirement asset. Right-sizing, renting, the Lease Buyback Scheme and keeping and adding each turn it into income in a different way; the right one depends on your age and your numbers.
find the age your own home could start paying you: five questions, free.
Find my Freedom Age
The check is free and needs no account. Two optional paid plans: the Freedom Plan, S$199 one-time, and the Freedom Plan with a 45-minute consultation, S$449 one-time. Nothing renews. Prices and terms.
Questions people ask
- How can I get a retirement income from my HDB flat?
- Four ways: sell and right-size (with the Silver Housing Bonus if eligible), rent out rooms or the whole flat after the MOP, sell part of the lease under the Lease Buyback Scheme from age 65, or use the flat as the base for a second property earlier in life.
- Is it better to sell or rent out my home for retirement income?
- It depends on the rent against the sale proceeds put to work, the loan left, and your age. Selling releases more at once; renting keeps the asset and its growth. Freedom Age compares both on your numbers.
- What is my Freedom Age?
- The age at which your property could start paying you the monthly income you want, from its sale, its rent or both, worked out from your household, income and home.
- What is the best way to retire on an HDB flat?
- There is no single best way: staying suits Lease Buyback, moving suits right-sizing. Compare them on your numbers.