The MOP: when your HDB flat can start working for you
You must live in a Standard or older flat for five years (ten years for Plus and Prime flats) before you can sell it on the open market, rent out the whole flat, or buy private property. After the MOP, a household with a Singapore citizen owner can keep the flat and buy a condo, but must keep living in the flat unless HDB approves renting it out, and pays ABSD on the condo as a second property.
What the MOP stops, and when it ends
| Flat | MOP |
|---|---|
| Standard, and flats sold before October 2024 that are unclassified | 5 years |
| Plus and Prime (including earlier PLH flats), new or resale | 10 years |
| Fresh Start Housing Scheme | 20 years |
Until the MOP ends you cannot sell the flat on the open market, rent out the whole flat, apply for an HFE letter to buy another flat, or acquire private property in Singapore or overseas. The MOP runs from the legal completion of your purchase and does not count time you did not live there.
The three moves the MOP unlocks
- Sell and upgrade. Sell the flat and buy a condo with no ABSD, because you own one home at a time.
- Keep and add. Keep the flat and buy a condo to rent out. As Singapore citizens this is a second property with ABSD of 20% (IRAS rates in force), and you must keep living in the flat.
- Rent out the whole flat. Allowed after the MOP with HDB's approval, except for Plus and Prime flats, which cannot be rented out whole.
Which move brings your Freedom Age forward
The earlier a larger asset is bought, the more years it compounds, which is why the sell-and-upgrade route often wins for couples in their thirties at MOP: one clean purchase, no ABSD, and a bigger base growing for thirty years. Keep-and-add wins when the flat is nearly paid and incomes can carry a second loan under the total debt servicing ratio, and the rent covers the 20% ABSD within a reasonable hold. Freedom Age prices each on your numbers and shows the age each one reaches.
A worked example: a couple of 34 and 33 at their MOP
The worked example follows a couple of 34 and 33 whose 4-room flat in District 19 is worth S$620,000, with S$300,000 of loan left and S$150,000 of CPF used. They earn S$7,500 and S$6,000 a month. Their first choice is a bigger condominium.
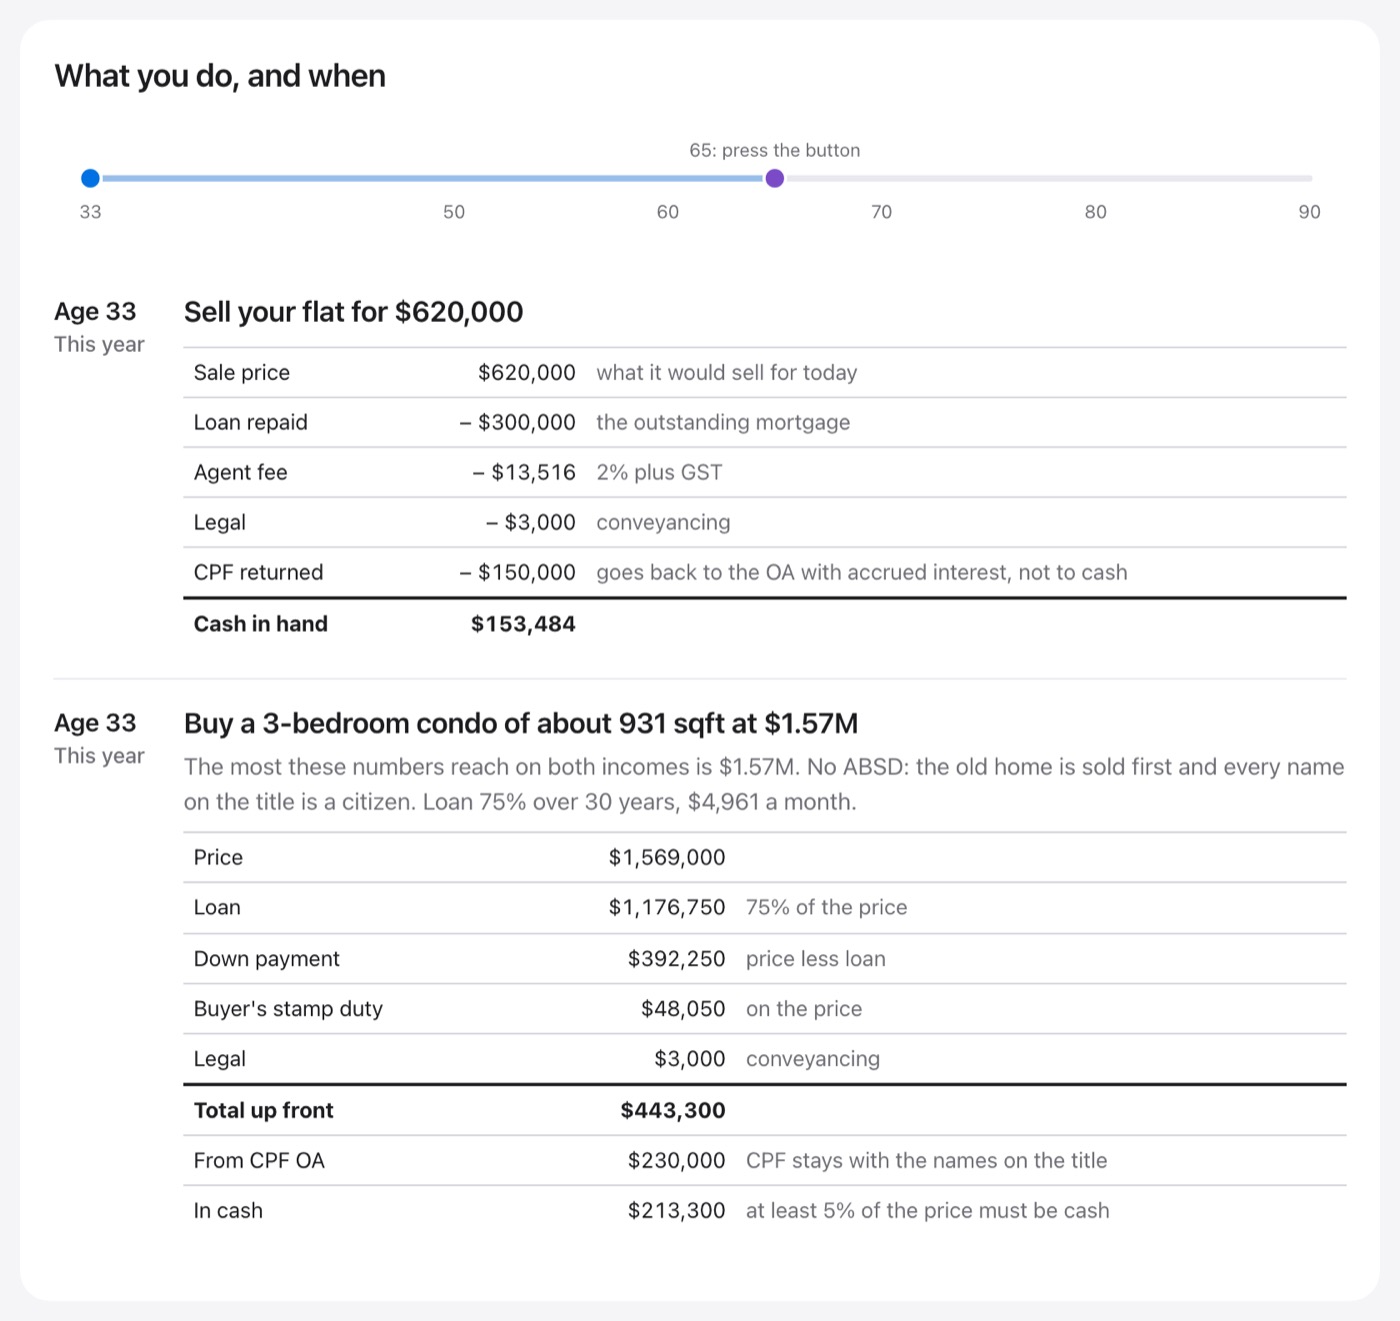
Selling leaves S$153,484 in cash after the loan, the S$13,516 agent fee, S$3,000 in legal fees and S$150,000 returned to CPF. On their two incomes the bank would lend on a price of up to about S$2.07 million, but the bank is not what stops them: their cash and CPF cover the down payment and duties up to about S$1.57 million. That buys a 3-bedroom of about 931 square feet at S$1,569,000: a S$1,176,750 loan over 30 years at S$4,961 a month, S$392,250 down. No ABSD applies because the flat is sold first and both names are citizens.
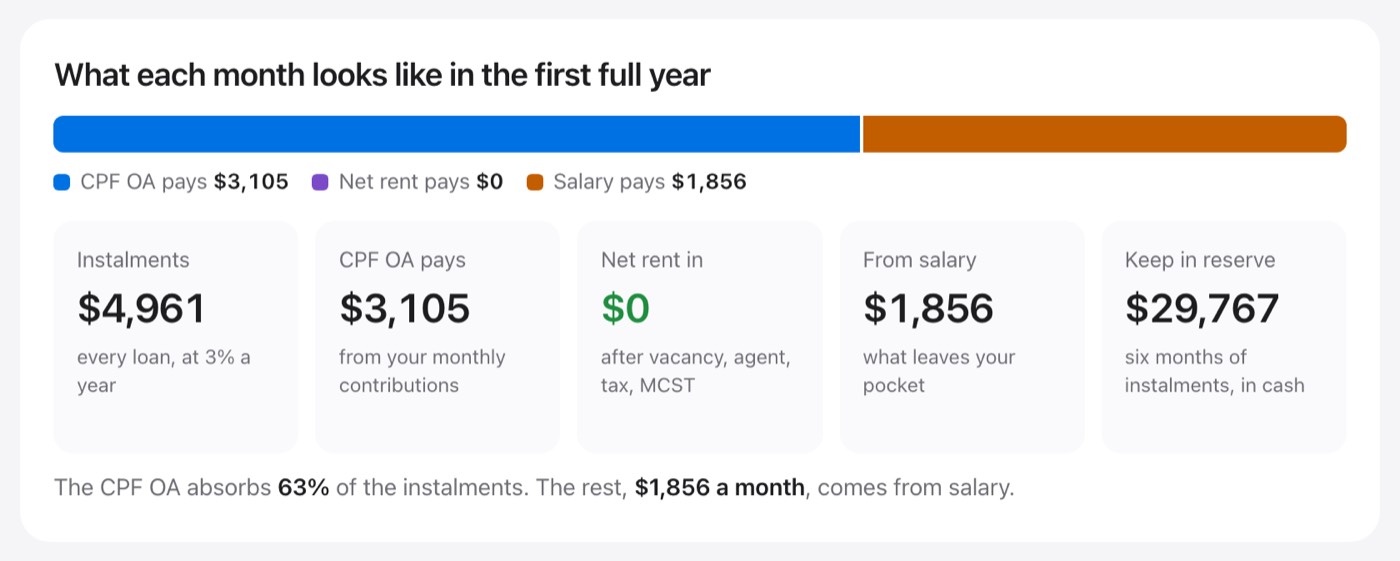
The trade is plain: S$1,856 a month from salary on top of CPF, and a reserve of S$29,767 (six months of instalments) set aside, in exchange for a larger asset growing for 30 years. Holding the flat instead, Freedom Age shows it worth about S$1.37 million at 65, fully paid.
Three ways to use the MOP, compared
| Sell and upgrade | Keep and add | Hold | |
|---|---|---|---|
| ABSD | None if sold first and all citizens | 20% on the condo for citizens | None |
| Loans | One, larger | Two | The current one |
| Monthly cash | Higher instalment | Two instalments, rent in | Unchanged |
| What grows | A larger asset | Two assets | The flat |
Before you decide at MOP
- Get your bank's ceiling on both incomes, then count the cash and CPF the down payment and duties need: in the example the bank would lend on up to S$2.07 million, but their cash and CPF stop at about S$1.57 million.
- Count the cash after the sale, not the sale price: S$153,484 in the example.
- Hold a reserve of six months of instalments before you commit.
- Run holding against moving: in the example the flat alone is worth about S$1.37 million at 65.
Renting out the whole flat after MOP
After the MOP, a Standard or older flat can be rented out whole with HDB's approval, subject to its conditions for you and your tenants. Plus and Prime flats cannot be rented out whole. Renting the whole flat means living elsewhere, so it usually pairs with a move, not with staying put.
Common mistakes
- Buying private before the MOP ends. It is not allowed until the MOP is met.
- Forgetting ABSD on keep-and-add. A citizen's second property carries 20% ABSD.
- Stretching to the ceiling. Leave room for a rate rise and a reserve.
The bottom line
The HDB MOP is the start line, not the finish: after it, selling and upgrading, keeping and adding, and holding each lead to a different retirement. Decide while the bank still lends over 30 years.
find the age your own home could start paying you: five questions, free.
Find my Freedom Age
The check is free and needs no account. Two optional paid plans: the Freedom Plan, S$199 one-time, and the Freedom Plan with a 45-minute consultation, S$449 one-time. Nothing renews. Prices and terms.
Questions people ask
- Can I buy a condo after my HDB MOP without selling?
- Yes, if at least one flat owner is a Singapore citizen. You must keep living in the flat unless HDB approves renting it out, and ABSD applies to the condo as a second property.
- What is the MOP for a Plus or Prime flat?
- Ten years, for new and resale Plus and Prime flats. Plus and Prime flats cannot be rented out whole.
- Does the MOP count time the flat was rented out?
- No. The MOP excludes any period you did not physically live in the flat.
- When can I rent out my whole HDB flat?
- After the MOP, with HDB's approval, unless it is a Plus or Prime flat.
- How much can we borrow for a condo after MOP?
- Banks cap total debt at 55% of gross monthly income and lend up to 75% for a first housing loan; Freedom Age works out your ceiling from your incomes and ages.
- Should we upgrade at MOP or wait?
- Earlier moves give the asset more years to grow and a longer loan; see the cost of waiting.
- Can I rent out my Plus or Prime flat after the MOP?
- Not the whole flat: HDB does not allow Plus and Prime flats to be rented out whole.