HDB Lease Buyback Scheme: sell part of your lease, stay put
The Lease Buyback Scheme lets flat owners aged 65 and above sell the tail end of their lease to HDB and keep living in the flat. The proceeds top up each owner's CPF Retirement Account (to the Basic Retirement Sum each for two or more owners), buy a CPF LIFE plan, and earn a cash bonus of up to $30,000; up to $100,000 of what is left can be kept in cash.
The top-up you must make first
For applications from 1 January 2026:
| Owner's age | One owner (to the age-adjusted Full Retirement Sum) | Two or more owners, each (to the age-adjusted Basic Retirement Sum) |
|---|---|---|
| 65 to 69 | $220,400 | $110,200 |
| 70 to 79 | $210,400 | $105,200 |
| 80 and above | $200,400 | $100,200 |
The bonus
Up to $30,000 for a 3-room or smaller flat, $15,000 for a 4-room and $7,500 for a 5-room or bigger flat. The household gets the full bonus when the total top-up is $60,000 or more; below that it is pro-rated ($1 for every $2 topped up on a 3-room or smaller, $1 for every $4 on a 4-room, $1 for every $8 on a 5-room or bigger). There is no bonus if every owner already had the Full Retirement Sum and needs no top-up.
How much lease you keep
| Youngest owner | Minimum lease kept | Other options |
|---|---|---|
| 65 to 69 | 30 years | 35 |
| 70 to 74 | 25 years | 30, 35 |
| 75 to 79 | 20 years | 25, 30, 35 |
| 80 and above | 15 years | 20, 25, 30, 35 |
The shorter the lease you keep, the more you unlock. After the top-up, up to $100,000 per household can be kept in cash; anything beyond goes to the Retirement Accounts up to the Full Retirement Sum before more cash is released. With at least $60,000 in the Retirement Account after the top-up, the whole account buys a CPF LIFE plan (not available from age 80).
HDB's example
A couple, both 65, own a fully paid 4-room flat worth $450,000 with 65 years of lease left. They keep 30 years and sell the last 35 years to HDB for $190,000. Each has about $20,000 in the Retirement Account, so about $90,000 each goes to reach the Basic Retirement Sum before the rest is paid out.
Buyback, right-size or rent out?
The buyback keeps you at home and turns part of the flat into a CPF LIFE payout. Right-sizing releases more, and can earn the Silver Housing Bonus, but means moving. Renting out a room keeps the whole lease. Freedom Age compares these on your numbers and shows which one reaches your monthly income target, and when.
A worked example: a couple of 62 and 60 in a fully paid 5-room flat
The worked example follows a couple of 62 and 60 in a fully paid 5-room flat in District 18 worth S$750,000, with S$180,000 of CPF used on it. They earn S$4,000 and S$2,000 a month and want S$3,500 a month in retirement.
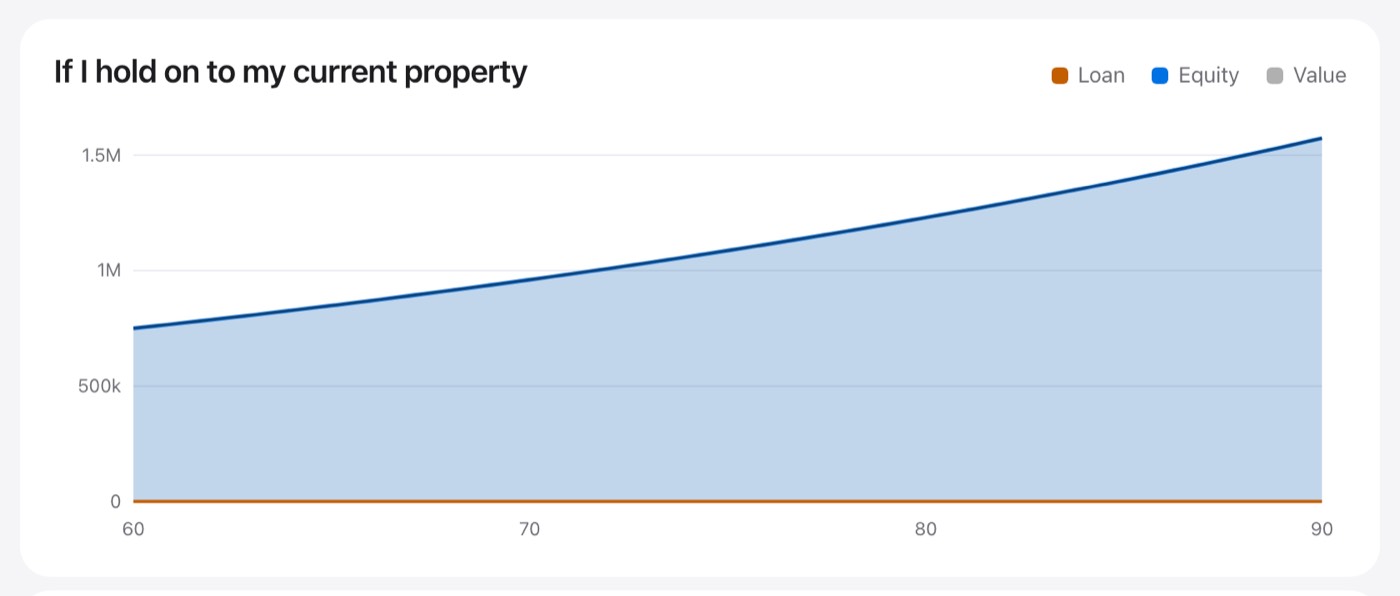
Keeping the flat, Freedom Age shows it worth about S$848,556 at 65, with nothing owed. That is wealth, but not income: it pays nothing a month until something is done with it. Their chosen move is to sell and buy a smaller home with cash in hand.
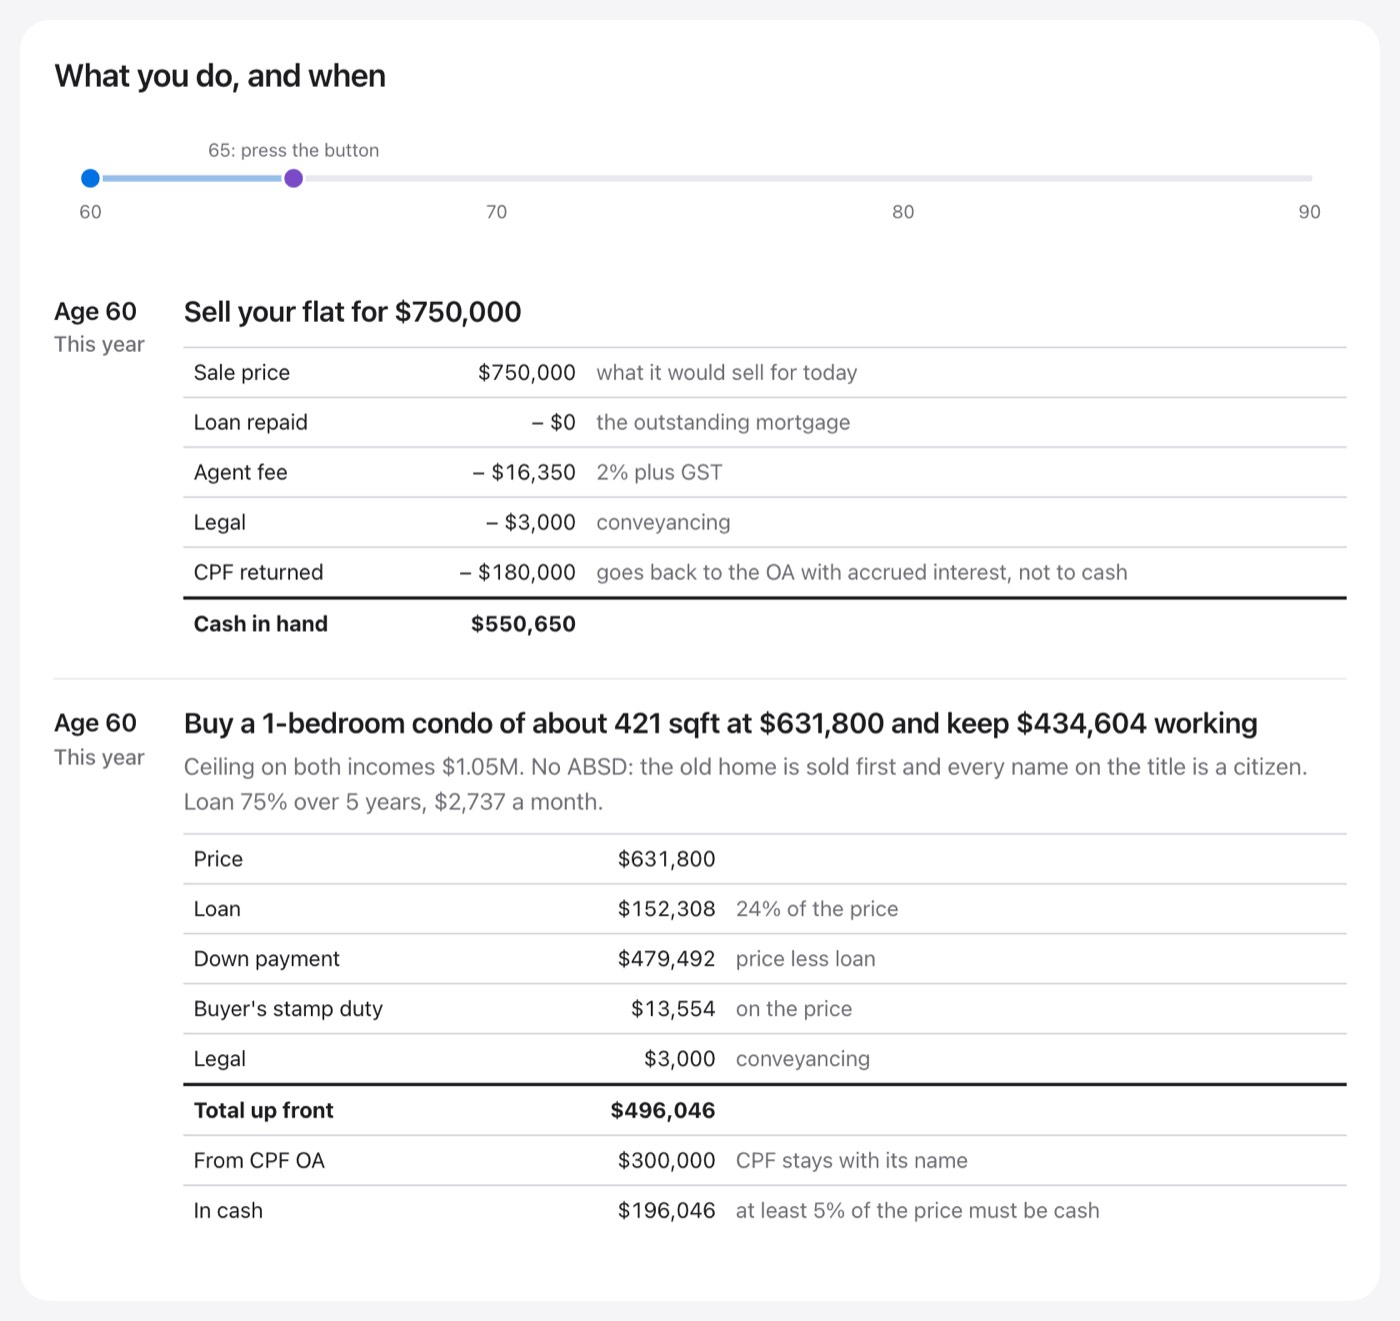
| The sale | |
|---|---|
| Sale price | S$750,000 |
| Agent fee (2% plus GST) | − S$16,350 |
| Legal | − S$3,000 |
| CPF returned to the Ordinary Accounts | − S$180,000 |
| Cash in hand | S$550,650 |
The tool sizes the next home to what the bank would lend and what keeps money working: a 1-bedroom condominium of about 405 square feet at S$608,400, a short loan of S$111,773 over three years at S$3,250 a month, and S$418,171 kept working. CPF pays S$1,380 of each instalment and S$1,870 comes from salary. The move turns a home that pays nothing into a smaller home plus a pot that pays, at the cost of three years of instalments that run to 65.
Lease Buyback or selling: how to compare
| Lease Buyback | Sell and right-size | |
|---|---|---|
| Stay in your home | Yes | No, you move |
| Main payout | A higher CPF LIFE payout, plus up to S$100,000 in cash | Net sale proceeds, plus the Silver Housing Bonus if eligible |
| Bonus | Up to S$30,000, S$15,000 or S$7,500 by flat size | Up to S$40,000 (Silver Housing Bonus) |
| What you give up | The tail end of the lease | The home itself and its space |
Before you apply
- Know the youngest owner's age: it sets the minimum lease you must keep.
- Check each owner's Retirement Account against the top-up requirement for their age.
- Estimate what the retained lease leaves your estate, and talk it through with your children.
- Compare with selling: Freedom Age shows what the same flat could pay if sold and right-sized.
Common mistakes
- Keeping more lease than you need. A longer retained lease unlocks less.
- Expecting all proceeds in cash. The Retirement Account top-up comes first; cash is capped at S$100,000 per household.
The bottom line
The Lease Buyback Scheme lets owners aged 65 and above stay at home and turn part of the lease into a lifelong CPF LIFE payout. Weigh it against right-sizing before you choose the lease to keep.
find the age your own home could start paying you: five questions, free.
Find my Freedom Age
The check is free and needs no account. Two optional paid plans: the Freedom Plan, S$199 one-time, and the Freedom Plan with a 45-minute consultation, S$449 one-time. Nothing renews. Prices and terms.
Questions people ask
- What is the minimum age for the Lease Buyback Scheme?
- The top-up requirements start at age 65, and the lease you keep is set by the age of the youngest owner, from 65.
- How much cash can I keep under the Lease Buyback Scheme?
- Up to $100,000 per household, after the Retirement Account top-up.
- What is the Lease Buyback bonus for a 4-room flat?
- Up to $15,000, in full when the household tops up $60,000 or more, pro-rated at $1 for every $4 below that.
- Do I have to move out under the Lease Buyback Scheme?
- No. You keep living in the flat for the lease you retain.
- How many years of lease must I keep at 70?
- If the youngest owner is 70 to 74, at least 25 years, with options of 30 or 35 (HDB).
- How much must two owners aged 65 each top up?
- For applications from 1 January 2026, each owner tops up to S$110,200, the age-adjusted Basic Retirement Sum for 65 to 69 (HDB).