The 15-month wait-out is gone. What it means if you are selling private to buy an HDB resale flat
Since 28 July 2026, private property owners and former owners can buy a non-subsidised HDB resale flat straight away, with no 15-month wait, as long as they do not take an HDB housing loan. They must still sell the private property within six months of completing the flat purchase. The 30-month wait still applies to a new HDB flat, a resale flat with CPF housing grants, a new EC from a developer, and any purchase with an HDB loan.
What changed on 28 July 2026
The 15-month wait-out was a cooling measure from 30 September 2022: a private owner had to sell, then wait 15 months, before buying a non-subsidised resale flat. Singapore citizens aged 55 and above moving to a 4-room or smaller resale flat were already exempt. HDB removed the wait with immediate effect on 28 July 2026, after the resale price index fell 0.1% in the first quarter and 0.3% in the second quarter of 2026.
What still applies
| Your purchase | Wait after selling private |
|---|---|
| Non-subsidised resale flat, bank loan or cash | None. Sell the private property within 6 months of completing the flat purchase |
| Resale flat with CPF housing grants | 30 months |
| New flat from HDB (BTO, SBF, open booking) | 30 months |
| New Executive Condominium from a developer | 30 months |
| Any flat with an HDB housing loan | 30 months |
You still need a valid HDB Flat Eligibility (HFE) letter before you take an option to purchase. The six-month disposal rule covers private property overseas as well as in Singapore.
The order of moves now
- Get the HFE letter, stating a bank loan or cash.
- Take the option on the resale flat and complete it.
- Sell the private property and complete that sale within six months of the flat completion.
Buying the flat before the private property is sold costs no ABSD when any buyer is a Singapore citizen: IRAS remits it in full on an HDB flat, automatically on HDB's approval. The gap you used to fund with rent is gone. What replaces it is a bridging question: for up to six months you hold both, so the flat's downpayment and the private property's loan run together. Bank loans for an HDB flat follow the bank's rules (75% loan-to-value on a first housing loan, the total debt servicing ratio of 55%, and the 30% mortgage servicing ratio for HDB flats), so the flat has to be financeable on your income alone while the private loan is still running.
Who this helps most
Owners of a condominium who want cash out for retirement without a year of renting in between, and couples whose children have left and who want a smaller home near family. It does not help a household that needs an HDB loan or a grant: that route still waits 30 months.
A worked example: a condominium couple of 58 and 56 right-sizing
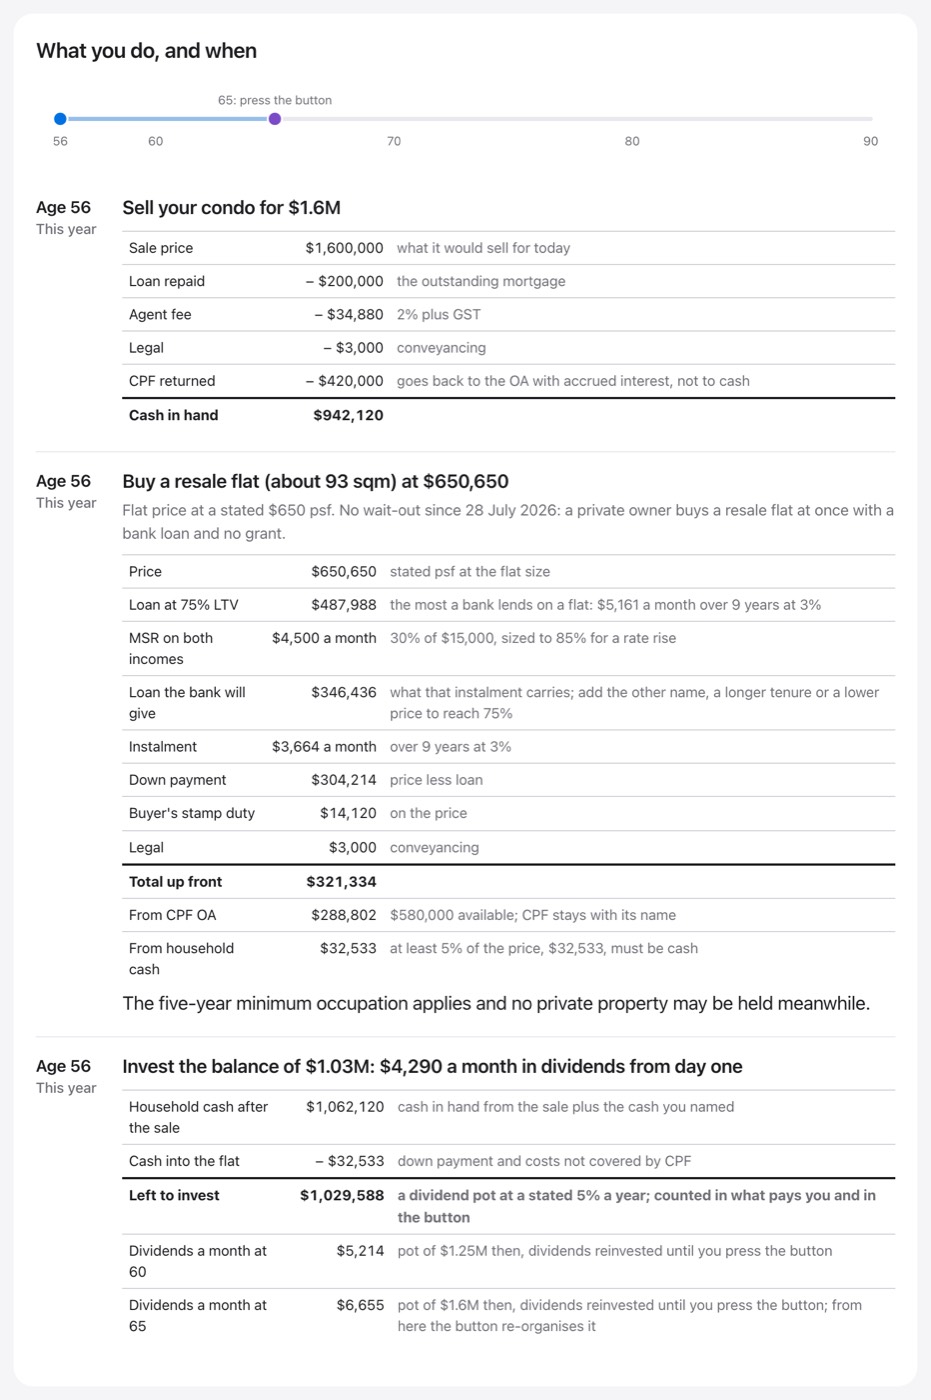
Freedom Age's worked example follows a couple of 58 and 56 in a District 15 condominium worth S$1.6 million, with S$200,000 of loan left and S$420,000 of CPF used on the purchase. They earn S$9,000 and S$6,000 a month and name S$5,000 a month as the retirement income they want. Their chosen move: sell, buy an HDB resale flat, invest the rest.
| The sale | |
|---|---|
| Sale price | S$1,600,000 |
| Loan repaid | − S$200,000 |
| Agent fee (2% plus GST) | − S$34,880 |
| Legal | − S$3,000 |
| CPF returned to the Ordinary Accounts | − S$420,000 |
| Cash in hand | S$942,120 |
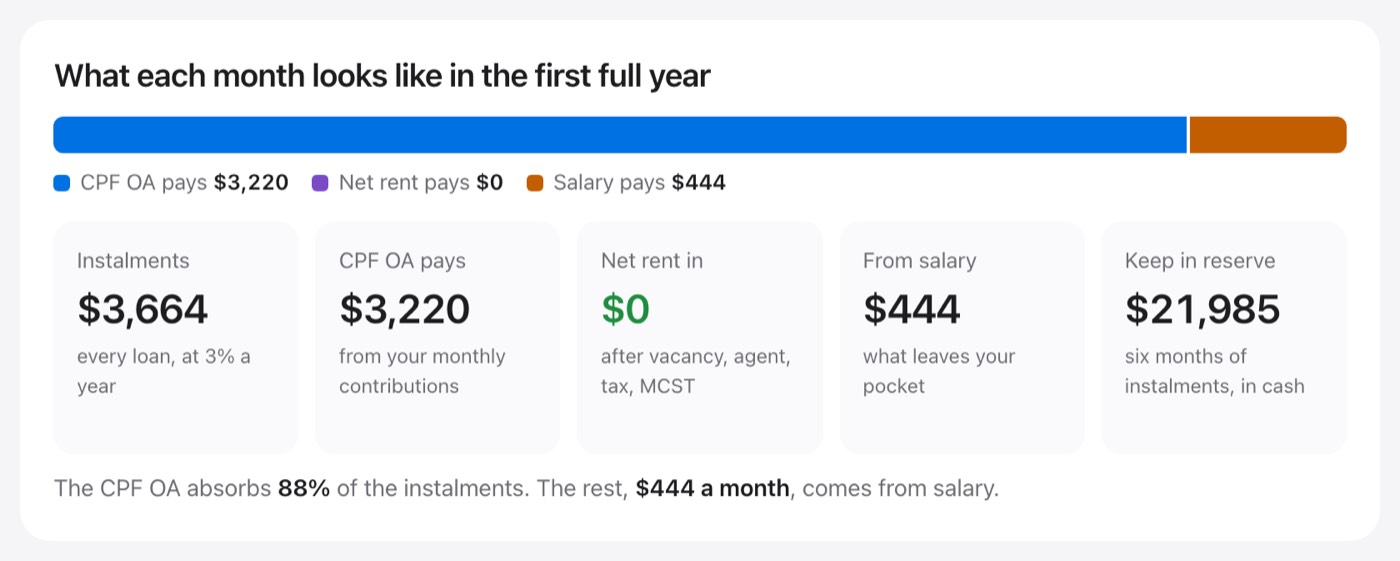
The flat, about 93 square metres, is priced at S$650,650 on a stated S$650 per square foot. Because they buy without an HDB loan there is no wait-out. The bank would lend up to 75%, but two limits bite: banks lend to about 65, so at 58 and 56 the loan runs only seven years, and the mortgage servicing ratio on their two incomes caps the instalment. What the loan does not cover, with the stamp duty and legal fees, comes from S$306,022 of CPF and S$32,532.50 of cash, the 5% of the price that must be paid in cash. The instalment is S$4,350 a month: CPF pays S$3,220 of it and S$1,130 comes from salary.
So they have more to invest than the sale's cash in hand: the flat takes only S$32,532.50 of their cash, and they already held S$120,000 of savings.
| What is left to invest | |
|---|---|
| Cash in hand from the sale | S$942,120 |
| Savings they already held | + S$120,000 |
| Cash into the flat (5% of the price) | − S$32,532.50 |
| Left to invest | S$1,029,588 |
At the tool's stated 5% a year, S$1,029,588 could pay about S$4,290 a month in dividends from the day they move.
Five checks before you sign
- Get the HFE letter first and state a bank loan or cash; an HDB loan brings back the 30-month wait.
- Ask your bank for an in-principle approval on the flat alone: for up to six months you hold both properties, and the flat must be financeable on your income while the private loan runs.
- Map the six months: list the private property early and price it to sell, because the disposal deadline counts from the flat's completion, not from when you are ready.
- Work out the CPF refund. The CPF used on the private property, with accrued interest, goes back to your CPF accounts, not to your bank account; count only the cash part as cash.
- Check your age against the loan: tenure generally runs to 65, so a buyer in their late fifties gets a short loan and a higher instalment, as the example above shows.
Common mistakes
- Treating the six months as a wait. It is a deadline to sell, and it starts when the flat completes.
- Counting the CPF refund as cash. In the example above, S$420,000 of the S$1.6 million sale goes back to CPF.
- Choosing an HDB loan by habit. The loan re-imposes a 30-month wait; a bank loan or cash does not.
The bottom line
The HDB wait-out period is gone for a non-subsidised resale flat bought without an HDB loan, but the six-month deadline to sell your private home, and the 30-month wait for loans and grants, remain. The order of moves decides the cost.
find the age your own home could start paying you: five questions, free.
Find my Freedom Age
The check is free and needs no account. Two optional paid plans: the Freedom Plan, S$199 one-time, and the Freedom Plan with a 45-minute consultation, S$449 one-time. Nothing renews. Prices and terms.
Questions people ask
- Is the 15-month wait-out period still in force?
- No. HDB removed it on 28 July 2026 for private property owners and former owners buying a non-subsidised resale flat without an HDB housing loan.
- Can I take an HDB loan after selling my condo?
- Yes, but then the 30-month wait-out applies after you sell the private property. The wait was removed only for purchases without an HDB loan.
- How long do I have to sell my private property after buying an HDB resale flat?
- Six months from the completion of the resale flat purchase, for property in Singapore or overseas.
- I already hold an HFE letter under the old exemption for a 4-room or smaller flat. Can I buy a 5-room now?
- HDB says you may cancel and re-apply for a new HFE letter if you wish to buy a 5-room or larger non-subsidised resale flat.
- Can I buy an HDB resale flat and sell my condo later?
- Yes, without an HDB loan: complete the flat purchase and sell the private property within six months of that completion.
- Does the CPF refund from my condo become cash?
- No. The CPF used on the condo, with accrued interest, returns to your CPF accounts; only what is left after the loan, fees and refund is cash.