Should you top up to the Enhanced Retirement Sum?
From 55 you can top up your CPF Retirement Account to the Enhanced Retirement Sum, S$440,800 in 2026, with cash or Ordinary Account savings. CPF estimates that a member who is 55 this year and reaches the ERS could receive up to about S$3,440 a month from 65, against about S$1,780 at the Full Retirement Sum. The top-up cannot be undone, and cash above the Full sum earns no tax relief. It suits people who want a larger income for life and still hold money they can reach; it does not suit anyone who may need the cash back.
The 2026 numbers
| Retirement sum | 2026 | 2027 | Estimated payout from 65 (turning 55 in 2026) |
|---|---|---|---|
| Basic | S$110,200 | S$114,100 | about S$950 |
| Full | S$220,400 | S$228,200 | about S$1,780 |
| Enhanced | S$440,800 | S$456,400 | up to about S$3,440 |
Since 2025 the ERS has been four times the Basic sum, double the Full. It is the same ceiling for everyone aged 55 and over, whichever year they turned 55, and it rises every 1 January, so there is room to top up again each year. CPF's payout guide gives a range of S$3,200 to S$3,400 a month from 65 for someone who turns 55 and tops up to the ERS in 2026, and S$2,600 to S$2,800 for someone who is 65 in 2026, set aside the Full sum at 55 and tops up now. The later you top up, the less the same ceiling buys.
How a top-up works
- Who. Members aged 55 and above, into their own Retirement Account, up to the current year's ERS. Family members can also top up for you.
- With what. Cash, or a transfer from your Ordinary Account.
- What it earns. The Retirement Account earned 4% a year for July to September 2026, against 2.5% in the Ordinary Account, before extra interest on the first S$60,000.
- Tax relief. Up to S$8,000 a year for cash you put into your own account and another S$8,000 for loved ones, but only up to the current Full Retirement Sum. The half between the Full and the Enhanced sum earns no relief, and nor does a top-up that attracts the Matched Retirement Savings Scheme grant.
- No way back. Cash top-ups and CPF transfers are irreversible. The money becomes monthly payouts, not a balance you can draw.
What the extra payout costs
Going from the Full sum to the Enhanced sum takes another S$220,400 and adds about S$1,660 a month from 65 on CPF's 2026 estimates: roughly S$75 a month for every S$10,000. Set that against the same S$10,000 kept outside CPF: at the 5% a year Freedom Age states for its dividend pot, which is an assumption and not a forecast, it pays about S$42 a month and the capital stays yours.
So CPF LIFE pays more per dollar, and pays it for life, but the capital is spent. Payouts of S$1,660 a month take about 133 months, some 11 years, to return S$220,400, so someone whose payouts start at 65 is ahead from about 76. A Singapore resident aged 65 can expect on average to live to 86.6, and half live longer. Whatever premium is unused when you die goes to your beneficiaries under CPF's rules.
Using the proceeds of a home sale
When you sell a home bought with CPF, the CPF you used plus accrued interest goes back to your CPF. If you are 55 or older, CPF first uses that refund to top up your Retirement Account to the Full sum; the balance stays in your Ordinary Account. From there you can keep it for your next home, leave it earning interest, withdraw it, or transfer it to your Retirement Account, up to the ERS.
The cash part of the proceeds can go in as a cash top-up, again up to the ERS. If you are right-sizing to a 3-room or smaller flat, the Silver Housing Bonus pays up to S$30,000 for committing up to S$60,000 to your Retirement Account, and that commitment can come from the housing refund. Do that first: it counts towards the top-up and earns a bonus as well.
ERS or FRS: which suits whom
| Top up to the ERS if | Stay at the Full sum if |
|---|---|
| You want a larger income that lasts however long you live | You may need the money for a home, care or family in the next ten years |
| You already hold a cash reserve and your home is paid for | Your cash reserve is thin or your loan runs past 65 |
| You expect a long life and have no one relying on a lump sum | You want to leave a larger sum, or can earn more elsewhere with risk you accept |
A worked example: a condominium couple of 58 and 56
Freedom Age's worked example follows a couple of 58 and 56 selling a District 15 condominium worth S$1.6 million, with S$200,000 of loan left and S$420,000 of CPF used on it. They buy an HDB resale flat of about 93 square metres at S$650,650 and invest the rest.
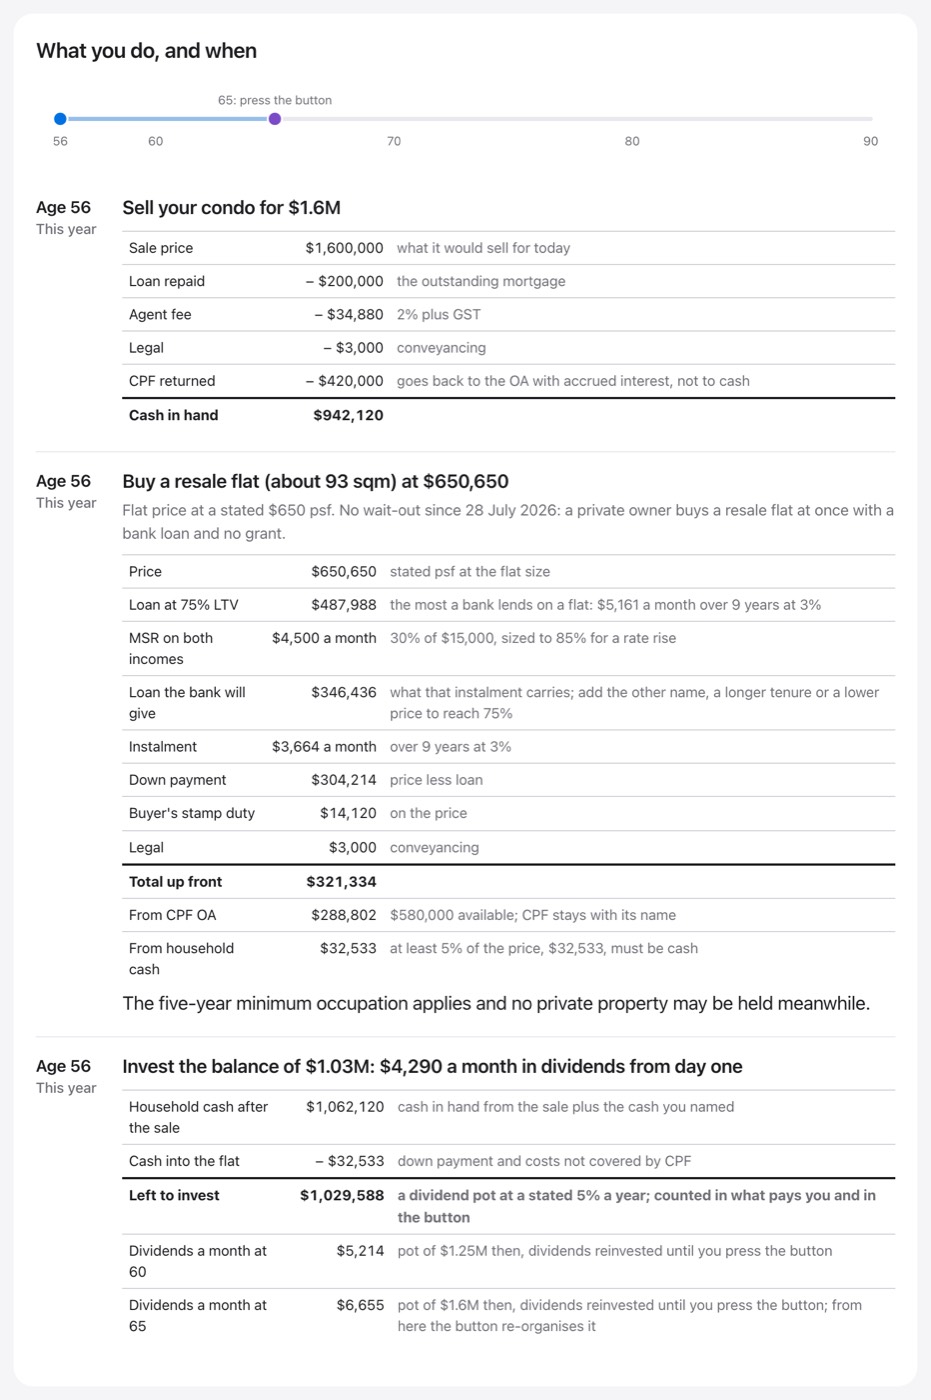
| The sale | |
|---|---|
| Sale price | S$1,600,000 |
| Loan repaid | − S$200,000 |
| Agent fee (2% plus GST) | − S$34,880 |
| Legal | − S$3,000 |
| CPF returned | − S$420,000 |
| Cash in hand | S$942,120 |
The tool counts S$580,000 of CPF Ordinary Account savings available for the flat, their own S$160,000 plus the S$420,000 refund, and uses S$288,802 of it. That leaves about S$291,198 of CPF across their two names. Their cash pot is S$1,029,588, which at the tool's stated 5% could pay about S$4,290 a month from day one.
Both partners are over 55, so under CPF's rule the refund first tops up each Retirement Account to the Full sum. Freedom Age shows the refund landing in the Ordinary Accounts, so check your own split on CPF's dashboard. If each Retirement Account already stands at the Full sum, each has room for another S$220,400 before the ERS, or S$440,800 for the two. The CPF left after the flat could fill about two thirds of that without any cash.
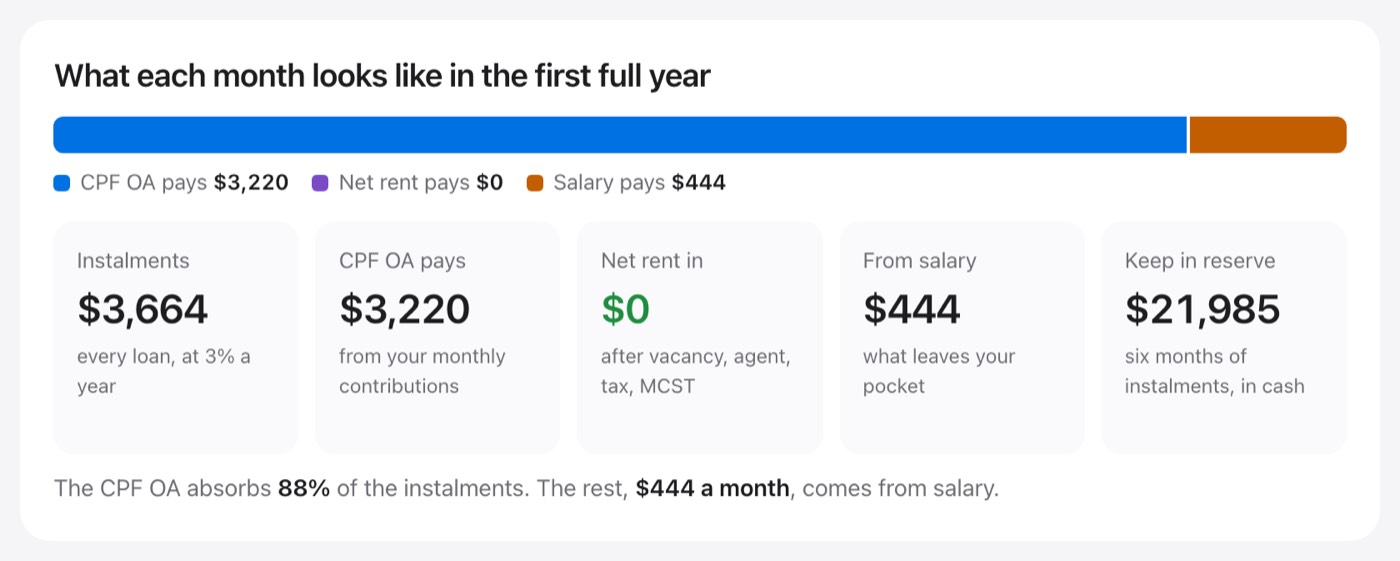
Should they? On CPF's figures each S$10,000 moved across buys roughly S$75 a month from 65, against about S$42 in the pot at a stated 5%. The pot's income starts now and stays theirs; the CPF income starts at 65 and lasts for life. Moving part of the CPF balance and keeping the pot as the reserve and the income until 65 is the kind of split the numbers point to. It is a planning illustration, not financial advice.
Before you top up: four checks
- Check your Retirement Account against the Full sum on CPF's Retirement dashboard, which also shows the most you can top up.
- Keep a cash reserve you can reach, and enough in the Ordinary Account for any housing loan.
- If you are right-sizing to a 3-room or smaller flat, commit the Silver Housing Bonus amount first.
- The ERS rises every January. Decide once a year how much more to move, rather than all at once.
The bottom line
Topping up to the Enhanced Retirement Sum buys a larger CPF LIFE payout for life, at the cost of money you can never take back. Do it with sale proceeds or savings you are sure you do not need, after a cash reserve and any Silver Housing Bonus commitment.
See a worked example in Freedom Age, then find the age your own home could start paying you: five questions, free.
Open the worked example
Questions people ask
- What is the Enhanced Retirement Sum in 2026?
- S$440,800, double the Full Retirement Sum of S$220,400. It rises to S$456,400 in 2027 (CPF Board).
- How much does CPF LIFE pay at the ERS?
- Up to about S$3,440 a month from 65 for a member who is 55 in 2026 and reaches the ERS, against about S$1,780 at the Full sum. CPF's payout guide gives S$3,200 to S$3,400 for someone who turns 55 and tops up in 2026.
- Can I top up the ERS with my HDB sale proceeds?
- Yes. From 55, the CPF refund first tops up your Retirement Account to the Full sum; the rest stays in your Ordinary Account and can be transferred to your Retirement Account up to the ERS. The cash proceeds can go in as a cash top-up.
- Do I get tax relief for topping up to the ERS?
- Only on cash top-ups up to the current Full Retirement Sum, up to S$8,000 a year for your own account. The part above the Full sum earns no relief (CPF).
- Can I withdraw an ERS top-up later?
- No. Cash top-ups and CPF transfers are irreversible; they come back to you as CPF LIFE payouts.
Sources
- CPF Board, What is the CPF retirement sum (2026 sums and payout estimates)
- CPF Board, What is the Enhanced Retirement Sum (ERS)?
- CPF Board, How much CPF monthly payout can I receive if I top up to the raised ERS in 2026?
- CPF Board, Top up to enjoy higher retirement payouts
- CPF Board, How much tax relief can I enjoy when I make cash top-ups?
- CPF Board, Selling your home: before vs after age 55
- CPF Board, CPF interest rates
- HDB, Silver Housing Bonus
- SingStat, Complete life tables for Singapore resident population 2024-2025