Is CPF LIFE enough? The honest answer for 2026
For basic needs, often yes; for the retirement most people describe, usually not. The Full Retirement Sum pays about S$1,780 a month from 65 for the 2026 cohort, below OCBC's estimate of S$2,725 per person for a basic retirement. It pays for life, which matters: a Singaporean who reaches 65 can expect, on average, to live to about 86.6.
The 2026 numbers
| Retirement sum (turning 55 in 2026) | Amount | Estimated monthly payout from 65 |
|---|---|---|
| Basic | S$110,200 | about S$950 |
| Full | S$220,400 | about S$1,780 |
| Enhanced | S$440,800 | about S$3,440 |
The sums rise every year: for 2027 they are S$114,100, S$228,200 and S$456,400.
What "73.4% hit the target" means
Of active members who turned 55 in 2025, 73.4% had the Full Retirement Sum or the Basic sum plus a property pledge, up from 70.5% a year earlier (CPF Board figures reported by The Straits Times). Hitting the target means reaching a payout set for basic needs, not a comfortable retirement.
Living longer than you plan for
Life expectancy at 65 is 86.6 years on average: 84.9 for men and 88.1 for women (SingStat, June 2026). Half live longer. That is why CPF LIFE's lifelong payout is valuable, and why a plan that runs out at 80 is not a plan.
What fills the rest
Three sources usually make up the difference: work (the retirement age rises to 64 and re-employment to 69 from 1 July 2026, and Budget 2026 raises contribution rates for those aged 55 to 65 from 2027), savings and investments, and the home. Freedom Age adds the home's income to the picture and shows when it could start.
A worked example: a single owner of 50
The worked example follows a single owner of 50 in a 4-room flat in District 23 worth S$560,000, with S$60,000 of loan left and S$140,000 of CPF used. They earn S$6,500 a month and want S$3,000 a month in retirement.
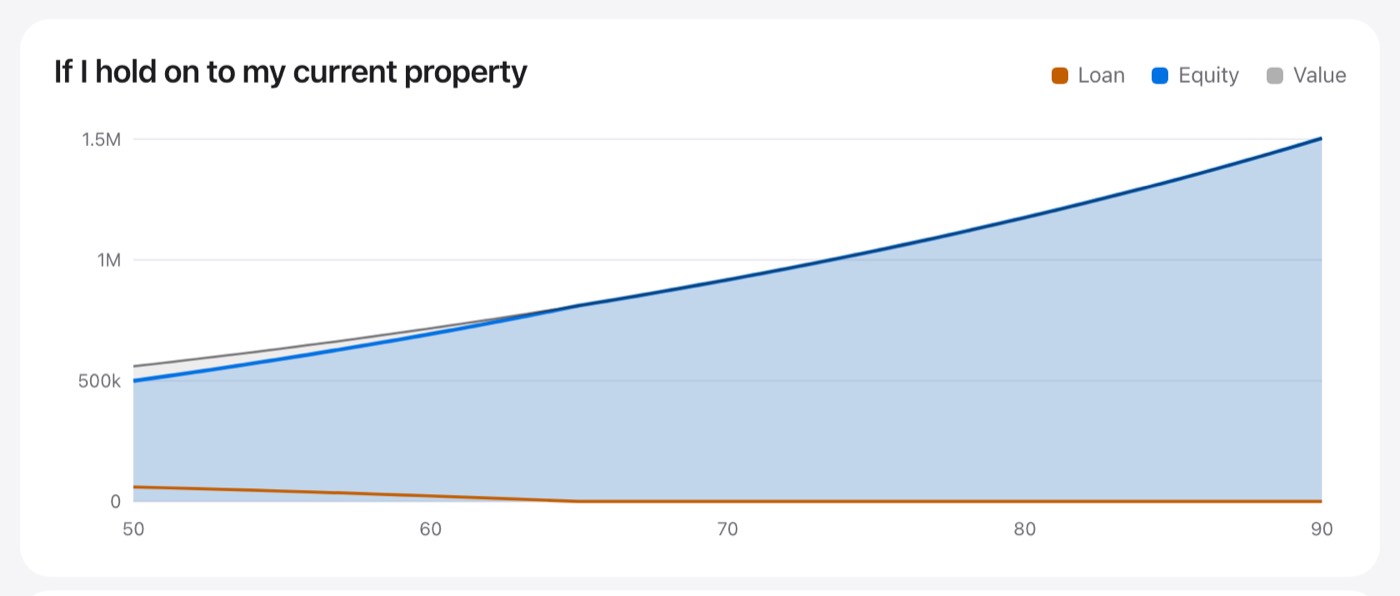
Held to 65, Freedom Age shows the flat worth about S$811,047, fully paid. Their chosen move is to sell and buy smaller while keeping money working.
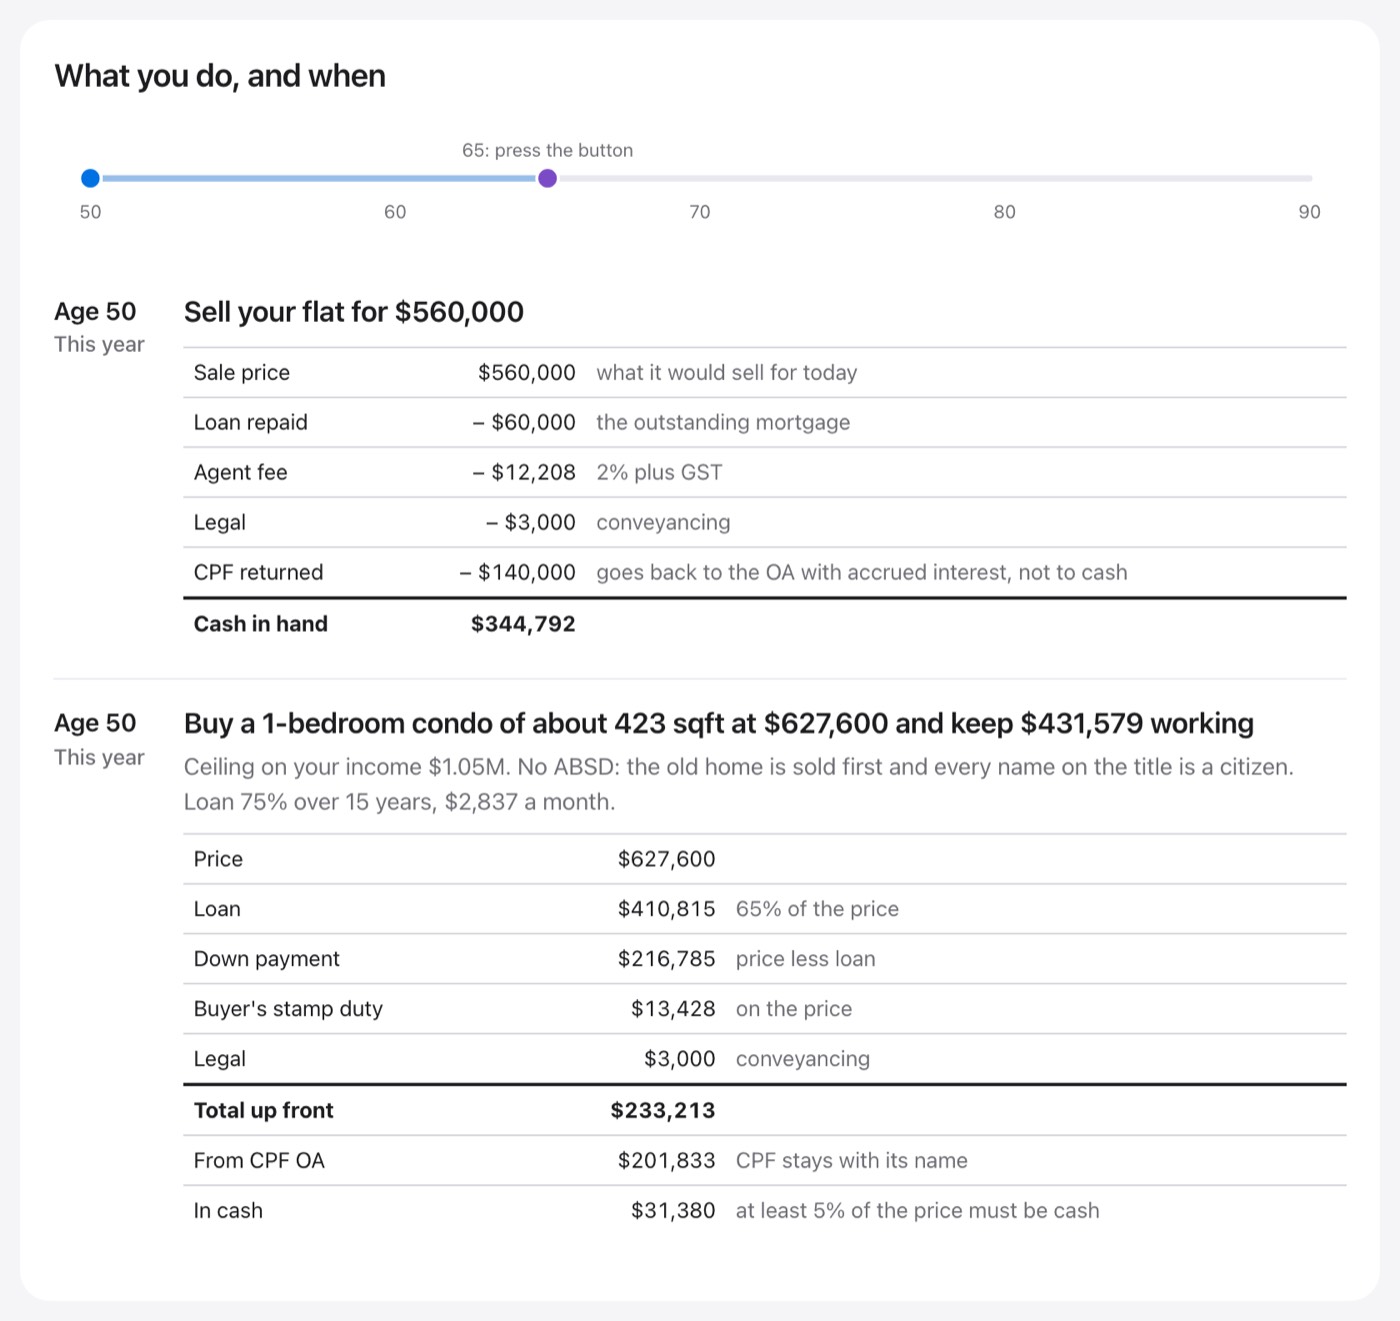
The sale leaves S$344,792 in cash after the loan, S$12,208 in agent fees, S$3,000 legal and S$140,000 back to CPF. The next home is a 1-bedroom condominium of about 423 square feet at S$627,600 on a 15-year loan at S$2,837 a month, with S$431,579 kept working. CPF pays 53% of the instalment; S$1,342 a month comes from salary until the loan ends.
What "enough" means, in three tiers
| Lifestyle (OCBC 2024, per person) | Monthly cost | CPF LIFE at the Full sum (2026) | Gap |
|---|---|---|---|
| Basic | S$2,725 | about S$1,780 | about S$945 |
| Mid-range | S$3,430 | about S$1,780 | about S$1,650 |
| High | S$6,150 | about S$1,780 | about S$4,370 |
Ways to close the gap
- Top up towards the Enhanced sum if you can spare the money and are content to lock it in.
- Work longer: re-employment runs to 69 from 1 July 2026.
- Turn part of your home into income, as the example above does with a smaller home and money kept working.
Standard, Escalating or Basic: choosing the plan
| Plan | How it pays | Suits |
|---|---|---|
| Standard | A level payout for life | Most people who want a steady base |
| Escalating | Starts lower, rises 2% every year | People worried about later-life prices |
| Basic | Lower payouts that fall once CPF balances go below S$60,000 | People who can live on less over time and want more left for family |
Whichever plan you pick, unused CPF LIFE premiums and any remaining CPF savings go to your loved ones when you pass away.
Deferring to 70
Payouts can start at 65 or be deferred up to 70. Each year of deferral raises the payout by up to 7%, so deferring to 70 could raise it by up to 35% (CPF). For someone who keeps working, or whose home already pays them, deferral turns a basic payout into a much larger one for the rest of their life.
The worked example above shows the other lever: a single owner of 50 who sells a flat worth S$560,000 and keeps S$431,579 working while living in a smaller home.
Common mistakes
- Reading "hit the target" as "comfortable". The Full sum is set for basic needs.
- Planning to 80. On average a 65-year-old lives to about 86.6, and half live longer.
- Ignoring the home. For most owners it is the largest asset and the one that can be turned into income.
The bottom line
CPF LIFE is a strong floor for basic needs and it pays for life, but for most people it is not the whole retirement. Deferral, the plan you choose and your home decide how far above the floor you live.
See a worked example in Freedom Age, then find the age your own home could start paying you: five questions, free.
Open the worked example
Questions people ask
- How much does CPF LIFE pay at the Full Retirement Sum?
- About S$1,780 a month from 65 on the Standard Plan for members turning 55 in 2026.
- Should I top up to the Enhanced Retirement Sum?
- It roughly doubles the payout to about S$3,440, but locks the money into CPF. Weigh it against what your home and other savings could pay.
- Should I defer CPF LIFE to 70?
- Deferring raises the monthly payout for each year of delay. It suits people with other income until then.
- What happens to my CPF LIFE when I die?
- Unused premiums go to your beneficiaries under CPF's rules; check CPF for how the bequest is worked out.
- Should I defer CPF LIFE if I am still working?
- If you can live on your salary, deferral raises your payout by up to 7% for each year, up to 35% at 70 (CPF).
- Which CPF LIFE plan pays the most?
- Standard pays more at the start; Escalating starts lower and overtakes it later because it rises 2% a year; Basic pays least each month.