How much do you need to retire in Singapore?
Start from the monthly gap, not a round number. OCBC puts a basic retirement at about S$2,725 a month per person and a mid-range one at S$3,430. CPF LIFE at the 2026 Full Retirement Sum pays about S$1,780 a month from 65. Over 25 years, to about 90, a basic gap of S$945 a month adds up to about S$283,500 and a mid-range gap of S$1,650 to about S$495,000, before growth and inflation. That is the sum to have by 65 on top of CPF. At 50 you have 15 years to build it; at 60, five.
Start with the monthly gap
| Lifestyle (OCBC 2024, per person, today's dollars) | A month | CPF LIFE at the Full sum (2026) | Gap a month |
|---|---|---|---|
| Basic | S$2,725 | about S$1,780 | about S$945 |
| Mid-range | S$3,430 | about S$1,780 | about S$1,650 |
| High | S$6,150 | about S$1,780 | about S$4,370 |
Your own number beats any survey. List what you spend now, take off what stops at retirement (the loan, the commute, the children), and add what rises with age, above all healthcare. What CPF pays you depends on the sum you set aside at 55: about S$950 at the Basic sum and up to about S$3,440 at the Enhanced sum.
Turn the gap into a lump sum
A Singapore resident aged 65 can expect on average to live to 86.6: 84.9 for men and 88.1 for women. Half live longer, so plan to 90 at least, which is 25 years of payouts from 65.
| Gap a month | 20 years (to 85) | 25 years (to 90) | 30 years (to 95) |
|---|---|---|---|
| S$945 (basic) | S$226,800 | S$283,500 | S$340,200 |
| S$1,650 (mid-range) | S$396,000 | S$495,000 | S$594,000 |
| S$4,370 (high) | S$1,048,800 | S$1,311,000 | S$1,573,200 |
These are the gap times twelve times the years, with no growth and no inflation. Growth on the sum helps you; rising prices work against you. At 2% inflation, prices rise by about half in 20 years, which is why a plan should test the later years at a higher cost, not today's.
What it takes at 50, 55 and 60
The sum at 65 is the same whatever your age today. What changes is the time to build it. Here is what a mid-range gap of S$495,000 asks each year:
| Your age now | Years to 65 | A year, with no growth | A year, at 5% growth (an assumption) |
|---|---|---|---|
| 50 | 15 | S$33,000 | about S$22,940 |
| 55 | 10 | S$49,500 | about S$39,350 |
| 60 | 5 | S$99,000 | about S$89,580 |
For a basic gap of S$283,500 the figures are S$18,900, S$28,350 and S$56,700 a year with no growth. The table shows why 50 is the age to decide: the saving is still affordable, and a home bought or sold then has 15 years to work.
Retiring at 55: the ten-year bridge
CPF LIFE starts paying at 65 at the earliest. Stop work at 55 and the first ten years have no CPF payout at all. At OCBC's basic cost of S$2,725 a month, those ten years alone take S$327,000 per person, on top of the sum that fills the gap after 65. At 55 you can withdraw the CPF savings above your Full Retirement Sum, or above the Basic sum if you own a property with a lease that runs to at least age 95 and pledge it. For most people, retiring at 55 is possible only if the home is part of the plan.
What S$500,000 or S$1 million could pay
| Sum at 65 | At 5% a year, capital kept | Drawn down evenly over 25 years, no growth |
|---|---|---|
| S$500,000 | about S$2,083 a month | about S$1,667 a month |
| S$1,000,000 | about S$4,167 a month | about S$3,333 a month |
The 5% is the yield Freedom Age states for its dividend pot, an illustration and not a promise; returns can be lower and capital can fall. Add CPF LIFE on top. A couple who each reach the Full sum draw about S$3,560 together, so S$500,000 kept working could take them past two basic lifestyles, and S$1 million past two mid-range ones. Where does the sum come from? For most Singapore owners, the largest part sits in the home.
A worked example: a single owner of 50
The worked example follows a single owner of 50 in a 4-room flat in District 23 worth S$560,000, with S$60,000 of loan left and S$140,000 of CPF used. They earn S$6,500 a month and name S$3,000 a month as the retirement income they want: a gap of about S$1,220 over CPF LIFE at the Full sum.
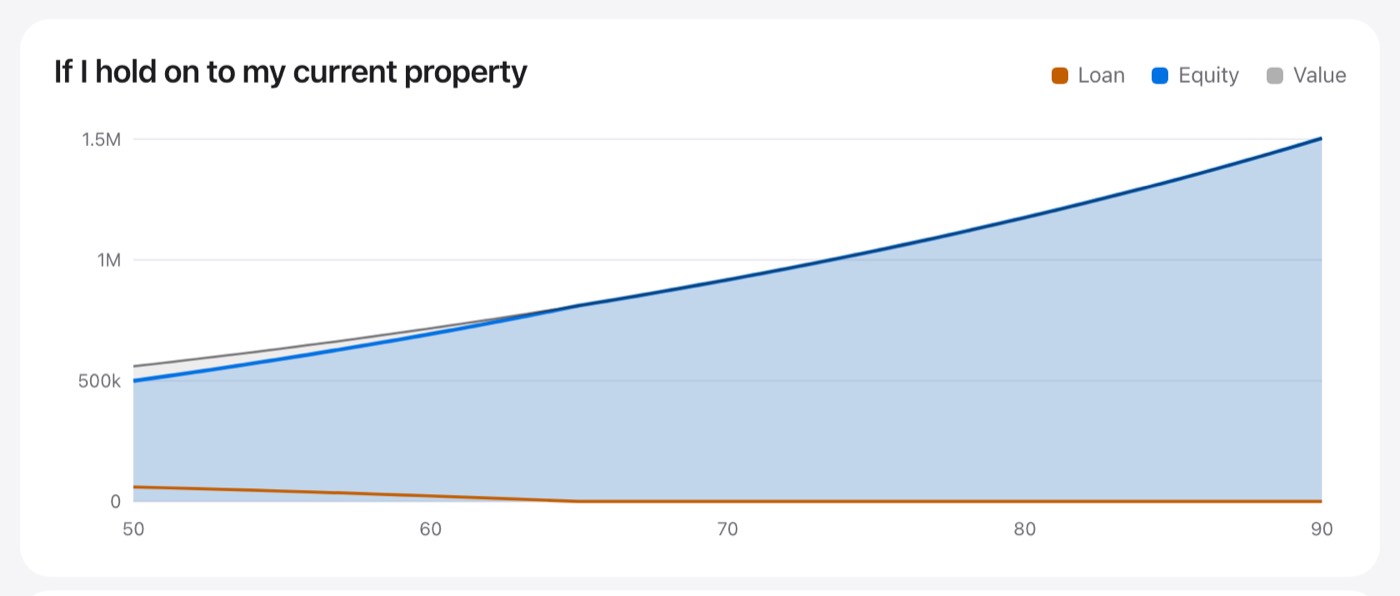
Kept, the flat is worth about S$811,047 at 65, fully paid, in Freedom Age's expected case. That is more than the mid-range sum in the tables above, but it pays nothing a month while they live in it.
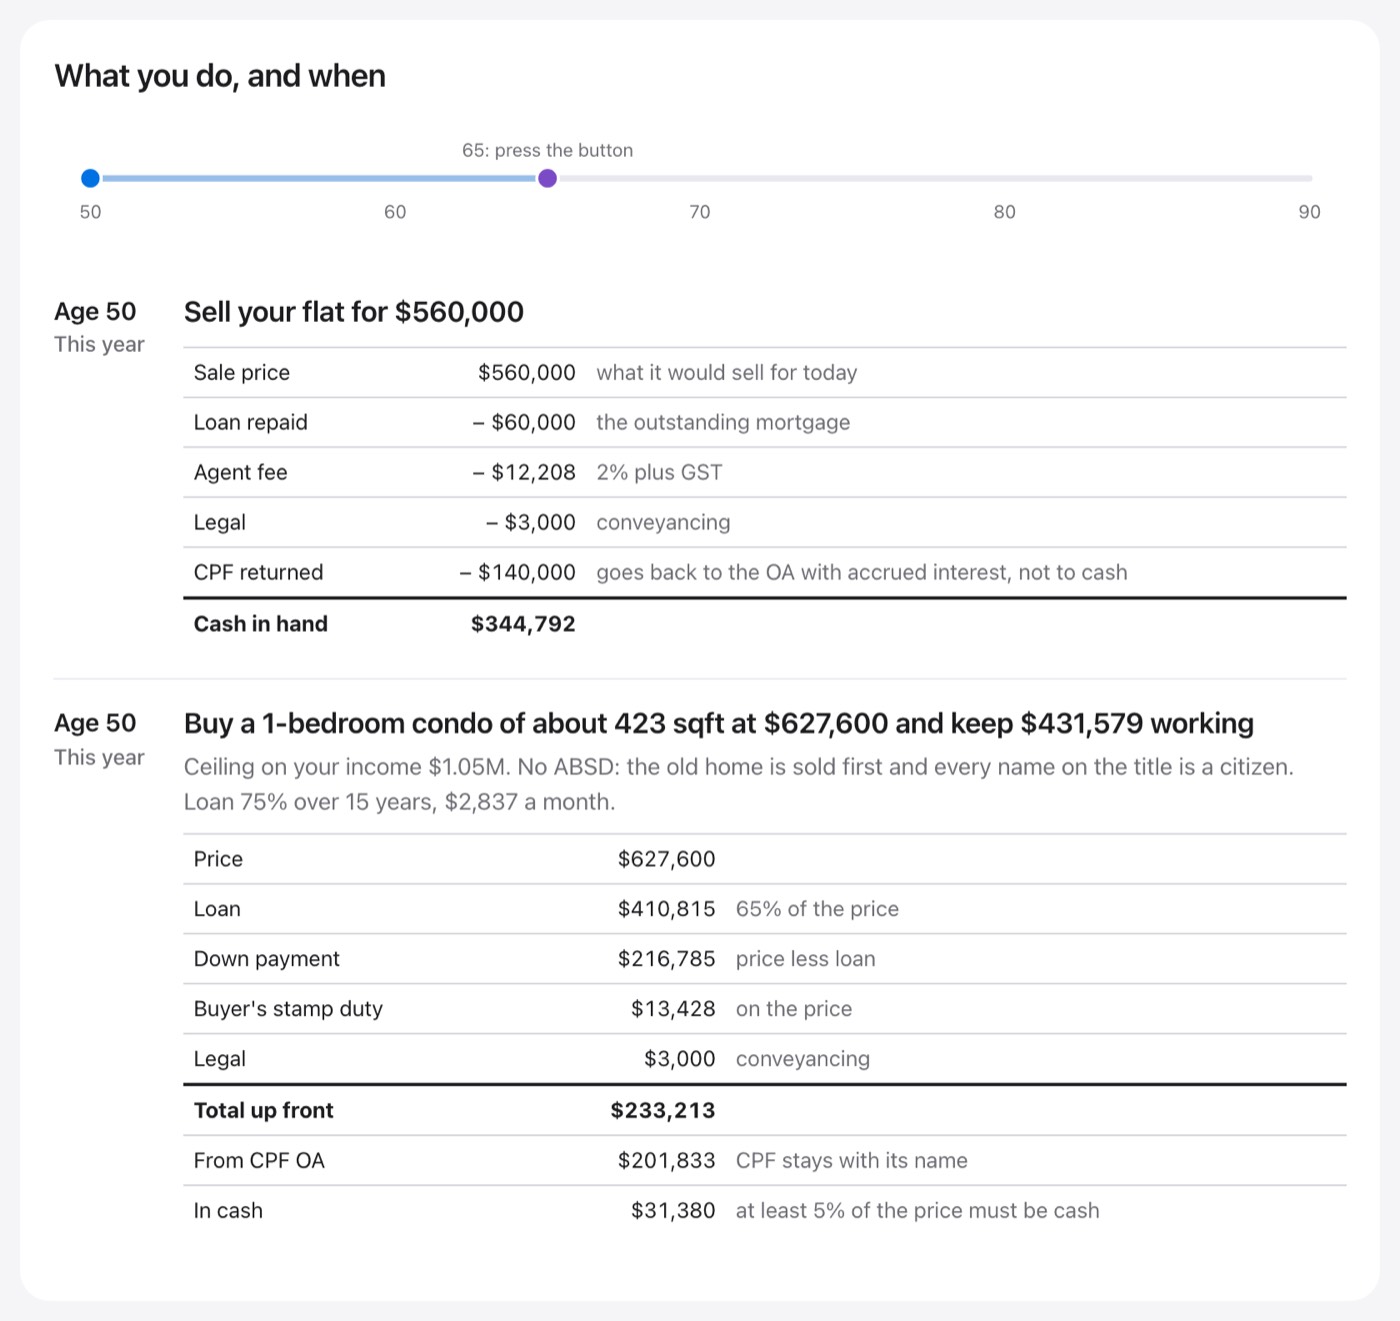
Their chosen move is to sell now and buy smaller. The sale leaves S$344,792 in cash after the loan, S$12,208 in agent fees, S$3,000 in legal fees and S$140,000 back to CPF. The next home is a 1-bedroom condominium of about 423 square feet at S$627,600 on a 15-year loan of S$2,837 a month, of which CPF pays 53%. S$414,792 goes into a dividend pot, which at the tool's stated 5% could pay about S$1,728 a month from day one: more than their S$1,220 gap, 15 years before CPF LIFE begins, while S$1,342 a month of the instalment still comes from salary until the loan ends.
Work out your own number in five steps
- Write down the monthly income you want in retirement, in today's dollars.
- Take off your CPF LIFE estimate from CPF's payout estimator.
- Multiply the gap by 12 and by the years from your retirement age to 90.
- Add the bridge: every year you stop before 65 costs a full year of spending.
- Set what you already hold against it, your home included, and see what is left to build.
The bottom line
How much you need to retire is the monthly gap after CPF LIFE, times the years you plan for, plus any years before 65. For most owners the home holds the largest part of that sum; the question is when it starts to pay.
See a worked example in Freedom Age, then find the age your own home could start paying you: five questions, free.
Open the worked example
Questions people ask
- How much do I need to retire in Singapore at 55?
- Enough to live on for the ten years before CPF LIFE starts at 65, about S$327,000 per person at OCBC's basic cost, plus the sum that fills the gap between CPF LIFE and your spending after 65.
- Can I retire with S$500,000 in Singapore?
- At a stated 5% a year it could pay about S$2,083 a month with the capital kept, or about S$1,667 a month drawn down over 25 years. With CPF LIFE on top, that covers a basic lifestyle for most people. It is not financial advice; returns can be lower.
- Is S$1 million enough to retire in Singapore?
- For most couples, yes for a mid-range lifestyle once CPF LIFE is added: about S$4,167 a month at a stated 5%, or S$3,333 a month drawn down over 25 years. A high-end lifestyle of S$6,150 a month each needs more.
- How much do I need to retire at 60 in Singapore?
- The same sum at 65 as anyone else, with five years to build it: for a mid-range gap of S$495,000, about S$99,000 a year with no growth.
- How much do I need to save from 50 to retire at 65?
- For a mid-range gap of S$495,000, about S$33,000 a year with no growth, or about S$22,940 a year at an assumed 5%.