The sandwich generation's way out
In Sun Life's 2026 survey, 80% of high-income Singaporeans expected to support their children or relatives in retirement; caring for both older and younger family members had led 45% to postpone retirement and 23% to lower their lifestyle expectations. The loop breaks when each generation's home pays its own way: the parents' flat through the Lease Buyback Scheme or right-sizing, and the middle generation's home through a plan made early.
Who is sandwiched
The middle generation pays for children at home and gives an allowance to parents who retired before CPF LIFE covered most of their needs. Sun Life found only 39% of its respondents very confident about their own retirement. Prudential's 2025 poll found Gen X the least confident generation, at 38%.
The allowance loop
An allowance paid to parents today is money the middle generation does not save, which makes it more likely their own children pay an allowance later. The loop runs as long as each generation retires short.
Breaking it with your parents' flat
Many parents own a paid-up HDB flat. Under the Lease Buyback Scheme, owners aged 65 and above can sell the tail end of the lease to HDB and keep living there; as at the end of 2024, 13,734 households had done so, most receiving between S$100,000 and S$300,000 (MND figures reported by The Straits Times). The proceeds top up CPF and buy a CPF LIFE payout, with up to S$30,000 in bonus and up to S$100,000 kept in cash. Seniors who right-size to a 3-room or smaller flat can receive a Silver Housing Bonus of up to S$40,000.
Breaking it for your children
The middle generation's own home is the lever it controls. The decisions made in the forties (upgrade, keep and add, or hold) decide whether the family home pays in retirement or has to be sold in a hurry. Freedom Age shows the age your home could start paying you, so the plan can be made while there is time.
A family plan
- Know your parents' position: flat, lease left, CPF balances.
- Check whether the Lease Buyback Scheme or right-sizing could replace the allowance.
- Run your own household in Freedom Age and fix the age your home pays you.
- Tell your children the plan, so they know they will not be the pension.
A worked example: parents of 44 and 42 with two teenagers
The worked example follows parents of 44 and 42 in a District 20 condominium worth S$1.4 million, with S$600,000 of loan left and S$300,000 of CPF used. They earn S$12,000 and S$8,000 a month, hold S$100,000 in cash and S$150,000 in their CPF Ordinary Accounts, and want S$7,000 a month in retirement. Their first choice is to keep the home and add a condominium to rent out.
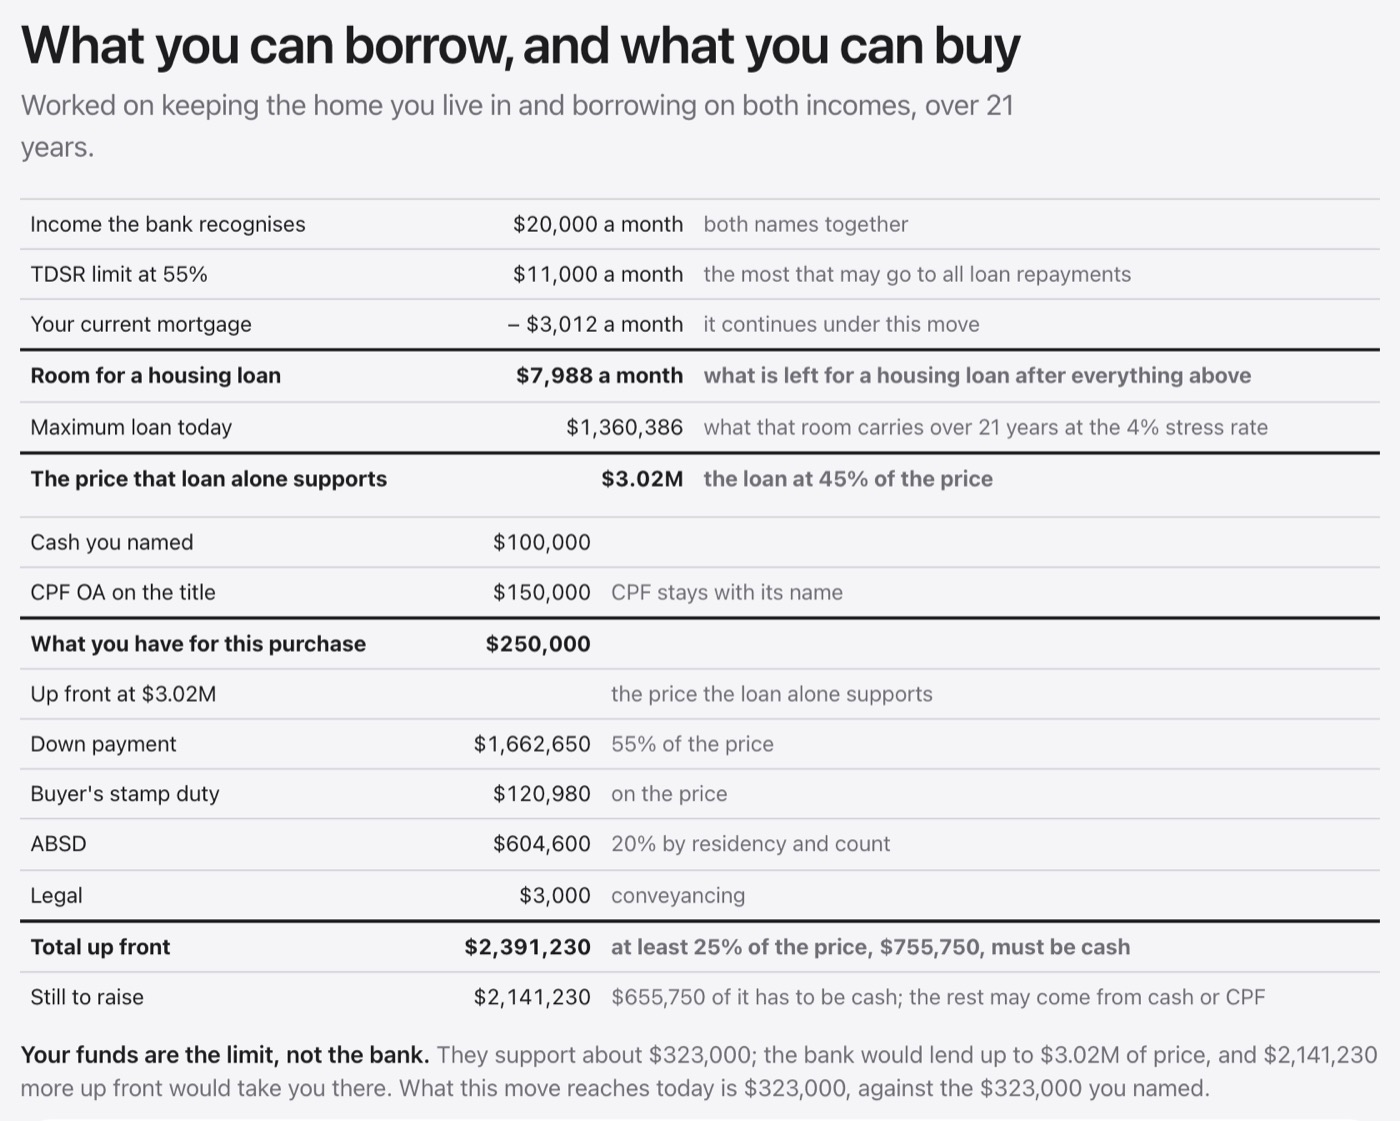
Income is not what stops them. With the home loan's S$3,012 a month still running, the bank would lend on a second property of up to about S$3.02 million. What stops them is cash. A second property takes a loan of at most 45%, so 55% of the price goes down, at least 25% of the price in cash, and 20% ABSD comes on top. Their S$250,000 of cash and CPF stretches to a price of about S$323,000, and nothing in District 20 sells for that: the lower quartile of one-bedroom asking prices there is about S$900,000. So Freedom Age prices the rental at that smallest unit. At S$900,000 it asks for S$699,600 up front, S$449,600 more than they hold, and at least S$125,000 of that has to be cash.
A home that cannot be bought on these numbers is not what the plan is built on, so the free page leads with keeping what they own. The keep-and-add card stays on the page with the gap in dollars and both pathways: the price the bank would lend against, and the price their own cash and CPF reach. Raising the S$449,600 is what could bring their first choice back.
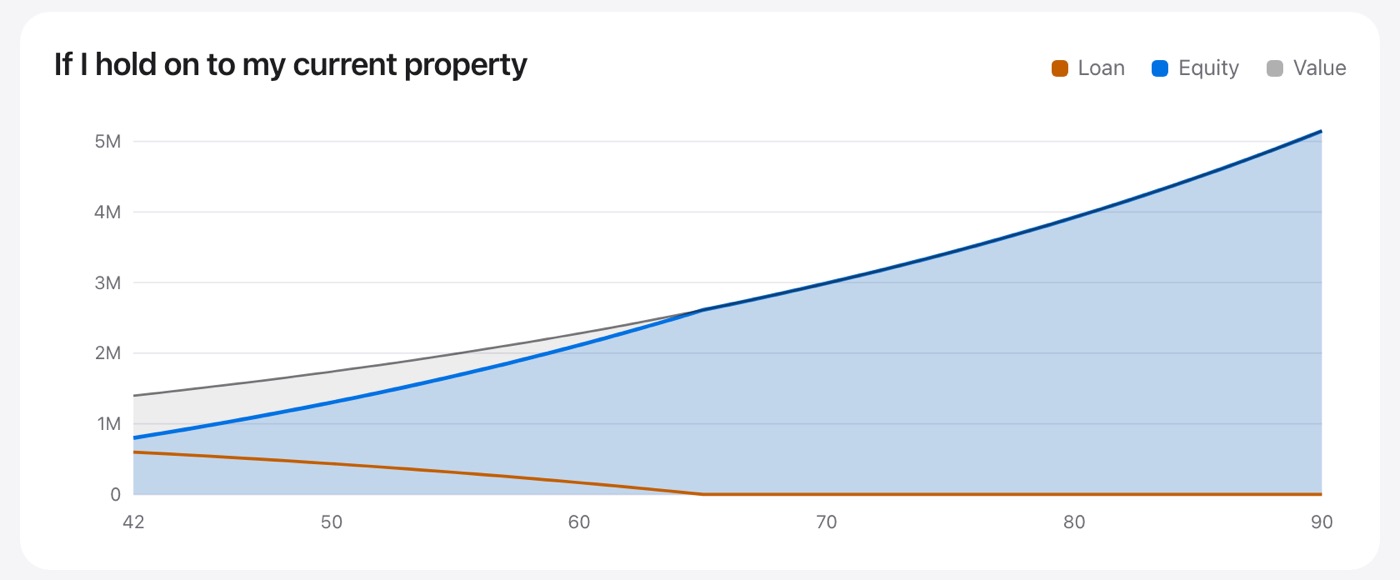
Holding what they own, Freedom Age shows the condominium worth about S$2.61 million at 65 with the loan paid off, and holding alone does not reach S$7,000 a month by 90. The moves that sell first and buy again are priced in the paid Freedom Plan, not in this free example. For a family facing university fees, the example makes one point plainly: a second property needs cash up front, the same cash the fees need, so the order of the two has to be settled before either is committed.
Mapping the three generations
| Generation | Main asset | Lever |
|---|---|---|
| Parents (65+) | A paid-up flat | Lease Buyback, right-sizing, renting a room |
| You (40s to 50s) | Your home and CPF | Upgrade, keep and add, or right-size, timed to your years |
| Children | Time | Loans and bursaries for study; no allowance owed to you |
A family conversation, in order
- Agree the facts: each generation's home, loan and CPF.
- Agree the goal: nobody depends on the next generation's allowance.
- Run the numbers for each home.
- Write down who does what, and when.
What the 2026 survey actually found
Sun Life's February 2026 survey of high-income respondents in Singapore found that 80% expect to keep working past retirement age, 48% because they need the income, and only 39% feel very confident about their retirement plans. Caring for older and younger family members had led 45% to postpone retirement and 23% to lower their lifestyle expectations; 80% expect to keep supporting their children or relatives in retirement. These are high earners: the pressure on the rest of the sandwich generation, on middle incomes, is unlikely to be lighter.
Common mistakes
- Paying the allowance without a plan to end it. Ask what would let your parents stand on their own.
- Borrowing long in your fifties for the children. Your loan tenure shrinks with age; a new long loan at 50 runs into retirement.
- Not telling your children. They plan better knowing they will not be your pension.
The bottom line
The sandwich generation breaks the allowance loop when each generation's home pays its own way: the parents' flat through Lease Buyback or right-sizing, and your own home through a plan made in time.
See a worked example in Freedom Age, then find the age your own home could start paying you: five questions, free.
Open the worked example
The check is free and needs no account. Two optional paid plans: the Freedom Plan, S$199 one-time, and the Freedom Plan with a 45-minute consultation, S$449 one-time. Nothing renews. Prices and terms.
Questions people ask
- Can my parents use the Lease Buyback Scheme?
- Owners aged 65 and above who meet HDB's conditions can apply. They keep living in the flat for the lease they retain.
- How much do households receive from the Lease Buyback Scheme?
- As at 31 December 2024, 13,734 households had joined; about nine in ten received between S$100,000 and S$300,000, as reported from MND figures.
- Will I have to depend on my children?
- Not if your home and CPF cover your needs. A plan made in your forties is the most effective protection.
- How much allowance do Singaporeans give their parents?
- There is no official figure for what families give; the better question is whether the parents' own flat could replace it.
- What share of Singaporeans delay retirement to support family?
- In Sun Life's 2026 survey of high-income Singaporeans, 45% had postponed retirement because of caring for older and younger family members.